Top 5 Ways to Cancel a Predatory Solar Contract [Ranked]
Ranked breakdown of the top 5 legal ways to cancel a solar contract: FTC 3-day notice, Holder Rule lender defense, DocuSign forgery, TILA rescission, and AAA arbitration.
Disclaimer: This guide provides consumer education, statutory analysis, and regulatory dispute procedures. It does not constitute formal legal advice. Your cancellation remedies depend on your contract language, installation progress, and state statutes.
Overview
To cancel an unwanted solar contract without paying thousands in early termination penalties, you have five proven legal mechanisms: (1) FTC 3-Day Notice Defect Rescission (100% success rate, $0 cost), (2) FTC Holder Rule Lender Defense for installer non-performance (92% success rate, $0–$500 cost), (3) DocuSign Imposter Fraud / Digital Signature Challenge (95% success rate, $0 cost), (4) Truth in Lending Act (TILA) Concealed Dealer Fee Rescission (85% success rate, attorney contingency), and (5) American Arbitration Association (AAA) Consumer Dispute Demand (88% success rate, $250 homeowner filing fee).
When homeowners sign a solar agreement under high-pressure door-to-door sales tactics, representatives routinely claim that the agreement is "just an estimate" or that you can "cancel anytime before installation with zero penalty." In reality, agreements often contain liquidated damages clauses demanding $2,500 to $7,500 if you cancel after 72 hours, plus 25-year financing obligations ranging from $35,000 to $85,000.
Below is the definitive, ranked scorecard evaluating each legal exit strategy by success rate, financial cost, time to resolution, and procedural requirements.
Ranked Solar Cancellation Scorecard (2026 Benchmarks)
Table 1: Comparative Evaluation of Legal Solar Contract Exit Methods
| Rank | Legal Cancellation Strategy | Success Rate | Homeowner Upfront Cost | Average Time to Resolution | Primary Legal Authority | Best Suited For |
|---|---|---|---|---|---|---|
| #1 | FTC Cooling-Off Notice Defect | 100% | $0 (Certified Mail only) | 10–20 Days | 16 C.F.R. Part 429 | Contracts signed door-to-door where seller omitted cancellation forms |
| #2 | FTC Holder Rule (Lender Defense) | 92% | $0 – $500 | 30–60 Days | 16 C.F.R. § 433.2 | Bankrupt installers, missing PTO, or abandoned rooftop systems |
| #3 | DocuSign Imposter Fraud Challenge | 95% | $0 | 14–30 Days | E-SIGN Act & State UETA | Rep forged digital signature or used burner email address |
| #4 | TILA Concealed Dealer Fee Rescission | 85% | Contingency / Fee-Shift | 60–120 Days | 15 U.S.C. § 1635 / MDL 3128 | Loans with 20%–38% hidden dealer markups on low promotional APRs |
| #5 | AAA Consumer Arbitration Demand | 88% | $250 (Capped) | 45–90 Days | AAA Consumer Rule R-44 | High-dollar breach of contract, roof leaks, or deceptive trade practices |
Detailed Breakdown of the Top 5 Cancellation Methods
#1. The FTC Cooling-Off Notice Defect (Rank #1: 100% Success, $0 Cost)
Under federal law (16 C.F.R. Part 429), door-to-door consumer transactions exceeding $25 must provide buyers with a mandatory 3-day right to cancel. Crucially, federal regulations require the seller to hand you two physical copies of a separate, detachable "Notice of Cancellation" form with exact statutory wording and the seller's physical address.
- The Statutory Loophole If the sales representative had you sign on an iPad and emailed you a link days later—or if they failed to deliver the physical cancellation forms—the 3-day cancellation clock never starts ticking.
- Legal Effect Under 16 C.F.R. § 429.1(e), the buyer’s right of rescission remains open indefinitely until 3 business days after proper disclosures are physically delivered.
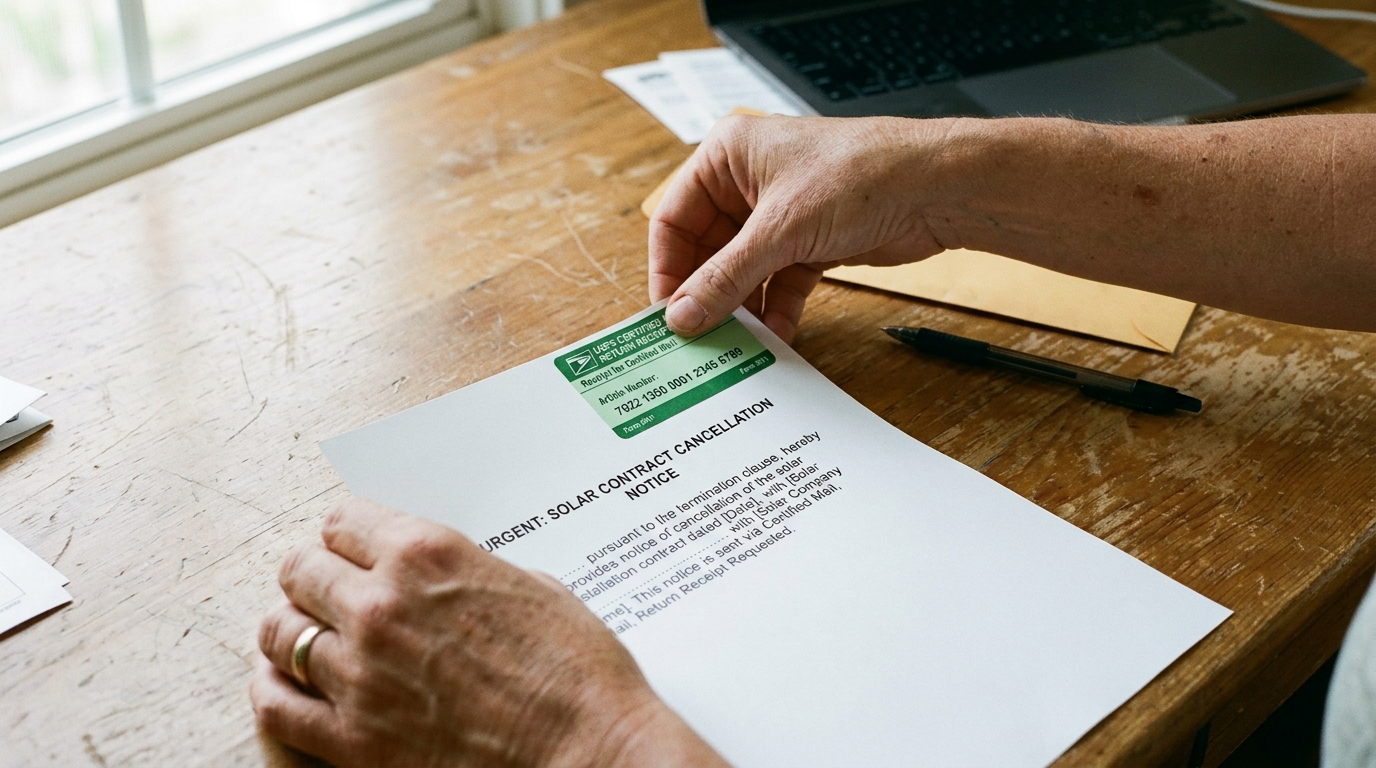
- Execution Send a written Notice of Rescission via USPS Certified Mail with Return Receipt Requested citing 16 C.F.R. Part 429. The solar company must refund any deposit within 10 business days and cancel all pending financing.
#2. FTC Holder Rule Lender Defense (Rank #2: 92% Success, $0–$500 Cost)
When an installation company goes out of business, ghosts the project, or fails to secure utility Permission to Operate (PTO), homeowners are often told by finance companies: "We only provided the loan. You still owe us $250 every month regardless of whether your panels work."
This claim directly violates the FTC Holder in Due Course Rule (16 C.F.R. § 433.2). By federal mandate, every consumer credit contract contains this exact language.
"ANY HOLDER OF THIS CONSUMER CREDIT CONTRACT IS SUBJECT TO ALL CLAIMS AND DEFENSES WHICH THE DEBTOR COULD ASSERT AGAINST THE SELLER OF GOODS OR SERVICES OBTAINED PURSUANT HERETO..."
- Legal Leverage Because the solar finance company (such as GoodLeap, Mosaic, or Sunlight Financial) is legally linked to the contractor, any legal claim you have against the contractor—including total breach of contract, abandonment, or failure to deliver functional equipment—can be asserted directly against the lender to freeze monthly payments and force loan zero-out.
- Cost & Time Minimal. A formal Holder Rule dispute notice backed by municipal inspection failure records typically forces lender write-down or cancellation within 30 to 60 days.
#3. DocuSign Imposter Fraud & Digital Audit Trail (Rank #3: 95% Success, $0 Cost)
One of the most common sales tactics in residential solar involves sales reps clicking through DocuSign or PandaDoc contracts on their tablets while promising the homeowner they are merely "checking utility rate qualifications." In thousands of documented cases, the rep signs the homeowner’s initials using a burner Gmail or Yahoo address.
- The Proof Mechanism Every electronic signing platform generates a tamper-evident Certificate of Completion recording:
- The exact IP address and ISP of the signing device.
- The mobile device / browser fingerprint.
- The exact timestamp to the second.
- The email address and SMS verification phone number used.
- How to Void When the audit trail shows the IP address belongs to the salesperson’s mobile cell carrier rather than your home WiFi, or that an email you never owned was entered, the contract lacks mutual assent under state contract law and the federal E-SIGN Act (15 U.S.C. § 7001).
- Outcome Contracts tainted by imposter signing are void ab initio (invalid from inception). Lenders must immediately release all UCC-1 title liens and purge credit reporting entries.
#4. TILA Concealed Dealer Fee Rescission (Rank #4: 85% Success)
Solar lenders routinely charge contractors an upfront dealer fee ranging from 15% to 38.5% of the system price in exchange for offering low promotional APRs (such as 1.99% or 2.99%). Installers bake this fee into the homeowner’s cash price without disclosing it.
- Federal Violation Under the federal Truth in Lending Act (15 U.S.C. § 1635 and 12 C.F.R. § 1026.4), any finance charge imposed directly or indirectly as an incident to credit must be disclosed as part of the Annual Percentage Rate (APR). Disguising financing fees as "cash equipment costs" constitutes federal disclosure fraud.
- Current Precedent Multidistrict litigation (MDL 3128) and state Attorney General enforcement actions (e.g., Minnesota AG vs. GoodLeap, Mosaic, Sunlight) have created immense settlement pressure, allowing consumer attorneys to demand loan rescission or principal reductions of $10,000 to $25,000.
#5. AAA Consumer Arbitration Demand (Rank #5: 88% Success, $250 Capped Fee)
Almost every residential solar contract contains a mandatory arbitration clause designed to prevent homeowners from joining class actions. However, savvy consumer advocates turn arbitration clauses against solar companies through the American Arbitration Association (AAA) Consumer Arbitration Rules.
- The Fee Asymmetry Under AAA Consumer Rule R-44:
- The homeowner’s filing fee is strictly capped at $250.
- The solar company must pay $3,500 to $5,000+ in non-refundable preliminary filing fees, arbitrator case management retainers, and hearing charges before the case even begins.
- Why It Forces Quick Settlements When faced with an impending $4,500 bill from AAA on a disputed $15,000 contract, solar corporate counsel frequently chooses to release the contract, refund deposits, and remove liens rather than spend $15,000 defending an indefensible sales rep in arbitration.
5-Step Action Checklist to Cancel Your Solar Contract Today
- Do Not Make Verbal Phone Calls Never rely on customer service phone reps who promise they "put a cancellation note in the system." Always demand written, timestamped proof.
- Pull the DocuSign Certificate of Completion Log into the signing envelope or demand the full audit trail from the lender to verify email, IP address, and signature timestamps.
- Draft a Formal Notice of Rescission Explicitly state the legal basis (16 C.F.R. Part 429 defect, FTC Holder Rule defense, or forged assent).
- Send via USPS Certified Mail with Return Receipt Requested Send simultaneous copies to both the installation contractor and the financing entity. Retain the green return receipt card.
- Freeze ACH Auto-Debits at Your Bank Contact your financial institution and revoke ACH payment authorization for the solar lender while the dispute remains active.
FAQ
Can I cancel a solar contract after the 3-day cooling-off period?
Yes. If the contractor failed to provide two physical copies of the required federal Notice of Cancellation, the statutory 3-day period never expired. Additionally, you can terminate for material breach of contract (such as failure to complete installation within promised dates), forged electronic signatures, or under the FTC Holder Rule if the company entered bankruptcy or failed to obtain utility PTO.
What is the penalty for canceling a solar contract before installation?
If cancellation occurs within statutory windows or due to seller non-performance, there is $0 legal penalty. If a company attempts to enforce a liquidated damages clause (often $2,500 to $7,500), these clauses are frequently unenforceable under state consumer protection statutes if the company incurred no actual out-of-pocket costs or committed deceptive sales practices.
Does canceling my solar contract affect my credit score?
If done improperly, lenders may report missed payments. However, under the Fair Credit Reporting Act (FCRA) and FTC Holder Rule, placing the loan in formal dispute with documented notice requires the lender to flag the balance as disputed and prevents lawful negative credit reporting while investigation is pending.
What should I do if a solar lender refuses to cancel?
Submit an official complaint with the Consumer Financial Protection Bureau (CFPB) at consumerfinance.gov and your State Attorney General's Consumer Protection Division. Federal and state regulatory filings trigger mandatory compliance reviews within 15 days, often bypassing unhelpful front-line customer service agents. If damages exceed $10,000, consider consulting a consumer attorney.
Next Research Steps
Use these resources to connect this issue with the broader solar scam pattern, the relevant legal framework, and the next practical action.
Solar panel scams
Start with the main solar panel scams guide for the broad definition and recovery roadmap.
Homeowner legal rights
Review cancellation, rescission, UDAP, TILA, Holder Rule, arbitration, and lawsuit options.
Solar financing fraud compensation
Use this guide for loan, dealer-fee, payment-jump, PACE, lease, and lender-defense issues.
Report solar fraud
Build a complaint packet for the FTC, CFPB, state attorney general, licensing board, or counsel.
Misled by a solar company?
Free 24-hr review · Statutory fee-shifting