Forged Sunlight Solar Loan? How to Prove It [Audit Guide]
How to audit DocuSign certificates of completion, prove signature forgery on a Sunlight Financial solar loan, and void fraudulent contracts ab initio.
Disclaimer: This article covers digital signature fraud, electronic evidentiary audits, and consumer-protection remedies under federal and state law. It does not constitute formal legal counsel. If you believe your identity was stolen or forged to execute a financing agreement, seek immediate assistance from consumer legal counsel and file an identity-theft report with law enforcement.
Direct Answer If a solar sales representative forged your signature on a Sunlight Financial loan agreement, the contract is void ab initio (invalid from inception) under the doctrine of fraud in the factum. To prove electronic signature forgery, homeowners must obtain the official DocuSign Certificate of Completion or Adobe Sign Audit Trail. These forensic records document the exact IP address, timestamp, device identifier, and delivery email used to sign the loan. Proving that the signing IP address matches the salesperson's mobile hotspot or a remote cellular tower rather than your home Wi-Fi network establishes conclusive legal evidence of signature fraud.
The Tablet Ambush: How Sales Reps Execute Digital Loan Forgery
Digital signature platforms like DocuSign and Adobe Sign were built to streamline commercial contracting. However, in the high-pressure, commission-only environment of door-to-door solar sales, predatory reps have repeatedly exploited electronic signatures to execute unauthorized six-figure financing packages.
The scheme frequently unfolds in one of two ways.
1. The "Qualification Screen" Finger-Swipe Trap
The salesperson brings an iPad to your door or kitchen table. They ask for your driver's license, claiming they need it to "verify utility net metering eligibility," "check roof sun-exposure maps," or "see if your address qualifies for federal grants." They hand you the tablet and ask you to swipe your finger across a glass box or initial a single block. Without your knowledge, the rep has loaded a 30-to-45-page Sunlight Financial promissory note with Cross River Bank. Your single finger-tap auto-populates initials and signature blocks across dozens of legal disclosures, arbitration agreements, and fixture lien waivers you never saw or read.
2. The Disposable "Burner Email" Scheme (Elder Exploitation)
In more egregious instances, the sales rep executes the entire transaction without the homeowner touching the screen at all.
Case In Point In rural Texas, a door-to-door sales representative targeting older homeowners visited an 84-year-old stroke survivor living on a $1,300/month fixed Social Security disability income. The salesperson claimed to represent a "county green energy program." After collecting the senior’s utility bill and identification under false pretenses, the rep created a disposable, burner Gmail address (e.g., <!--email_off-->[email protected]<!--/email_off-->).
The representative intercepted the DocuSign loan envelope dispatched by Sunlight Financial and forged digital signatures on a $113,000, 25-year solar financing note. The senior only discovered the debt six months later when Cross River Bank issued default notices.
In a landmark 2026 arbitration proceeding, consumer counsel subpoenaed the DocuSign audit trail. The records revealed that the envelope was signed from a mobile cell tower IP address located 40 miles away from the home—matching the sales rep’s phone tower location. The arbitrator issued an award ordering Sunlight Financial to void the $113,000 note entirely, file a UCC-3 termination statement to clear the property title, and award statutory damages for elder financial exploitation.
Digital Forensics: How to Obtain and Read the DocuSign Certificate of Completion
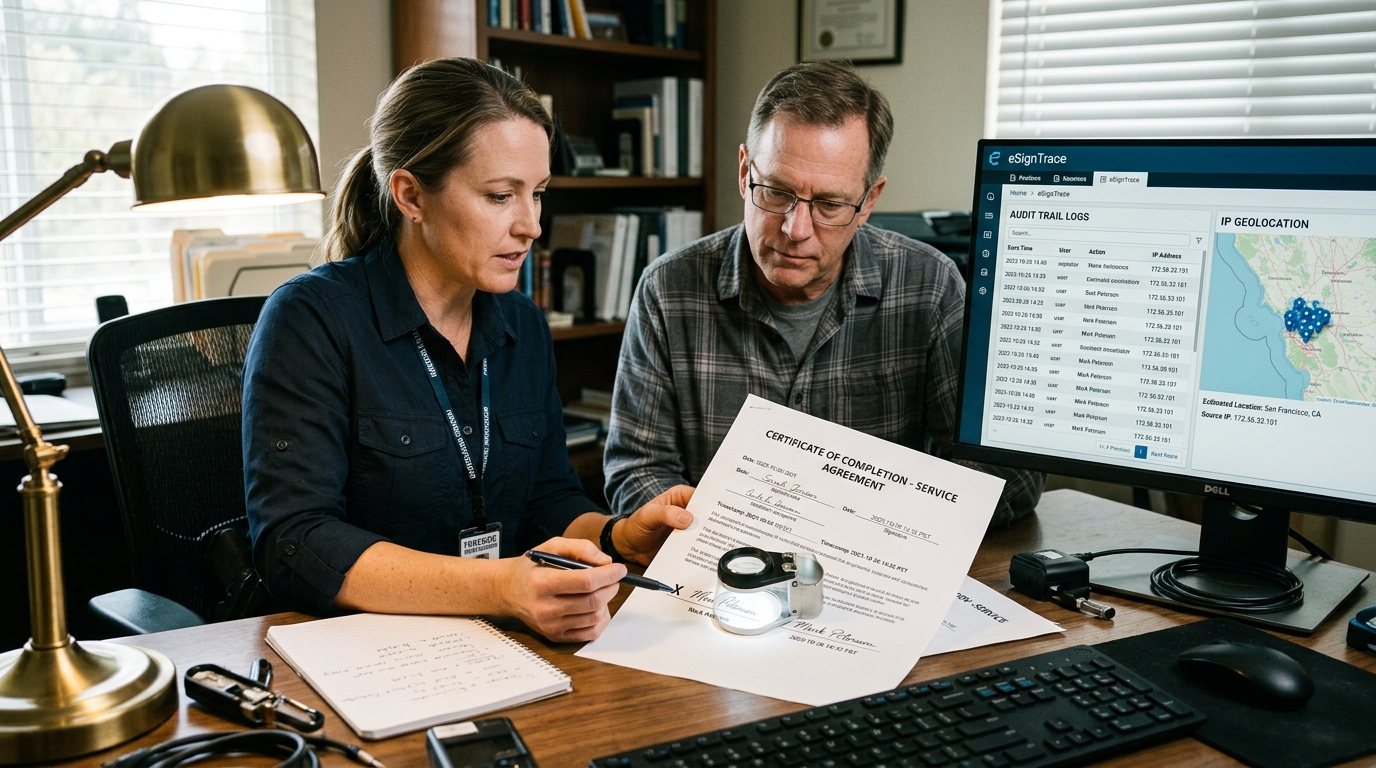
To defeat a forged loan agreement, you cannot simply say, "That doesn't look like my signature." Because digital signatures generate pre-formatted cursive fonts, you must attack the metadata behind the envelope.
Every e-signature platform creates an immutable digital audit trail. For DocuSign, this document is called the Certificate of Completion.
graph TD
    A[DocuSign Envelope Created] --> B[Envelope Sent to Delivery Email]
    B --> C[Signer Opens & Views Document]
    C --> D[Signer Executes Signature]
    D --> E[DocuSign Generates Certificate of Completion]

    E --> F{Forensic Audit Checklist}
    F --> G[1. Check Signer Email: Is it your real email or a burner?]
    F --> H[2. Check Signing IP Address: Does it match home router or rep's cellular IP?]
    F --> I[3. Check Time on Page: Was a 40-page contract signed in 22 seconds?]
What the Certificate of Completion Contains:
- Signer Email Address: Look closely at the recipient email. Reps often create variations of your name with random numbers on Gmail, Yahoo, or Outlook that you have never owned.
- IP Address & Geolocation: The certificate records the public IPv4 or IPv6 address from which the document was opened and signed. If you were at home connected to your residential broadband (e.g., Comcast, AT&T, Spectrum), your signing IP will correspond to your home internet provider. If the IP resolves to a mobile carrier network (T-Mobile, Verizon Wireless) matching the rep's smartphone, that is direct evidence of third-party execution.
- Time-on-Page Stamps: The certificate records timestamps down to the millisecond. If the audit trail indicates that a 40-page Truth in Lending disclosure packet was opened, scrolled, and signed in 28 seconds, no reasonable court or arbitrator will accept that the consumer reviewed the contract.
- Security & Authentication Verification: Legitimate financial transactions often require SMS two-factor authentication or knowledge-based authentication (KBA). If the rep bypassed security by selecting "No Authentication Required" or inputted their own cell phone number to receive the verification SMS, the fraud is cemented.
Legal Repercussions: Fraud in the Factum vs. Fraud in the Inducement
Under contract law and Uniform Commercial Code UCC § 3-305(a)(1), there is a profound distinction between two types of fraud:
- Fraud in the Inducement: The consumer knowingly signed the contract, but did so based on false promises (e.g., "solar will cut your power bill to $0"). The contract is voidable, but the lender may claim defenses if they are an innocent third-party holder.
- Fraud in the Factum (Execution): The consumer was deceived as to the very character or essential terms of the document, or their signature was placed on the note without their knowledge or consent.
Legal Result Fraud in the factum makes the contract void ab initio—it is a legal nullity that never existed. Even a holder in due course cannot enforce an instrument procured through fraud in the factum. Sunlight Financial and Cross River Bank cannot collect a single dollar, cannot report negative data to credit bureaus, and cannot maintain a property lien on a note procured through signature forgery.
4-Step Checklist to Invalidate a Forged Sunlight Financial Loan
If you suspect your digital signature was forged on a Sunlight Financial agreement, take these steps immediately.
Step 1: Demand the Complete E-Signature Audit Trail
Send a formal written request to Sunlight Financial's legal compliance and fraud investigation departments:
- Request the complete, unredacted promissory note PDF along with the full DocuSign Certificate of Completion and envelope history.
- Do not accept a basic summary page; demand the multi-page technical audit log showing IP addresses, browser user-agents, and timestamps.
Step 2: File an Identity Theft Report
File an official identity-theft report with the Federal Trade Commission at IdentityTheft.gov and file a police report with your local municipal police department or sheriff’s office.
- List the unauthorized execution of credit by the solar installation company and Sunlight Financial.
- An official FTC Identity Theft Report triggers mandatory protections under the Fair Credit Reporting Act (15 U.S.C. § 1681c-2), forcing credit bureaus to block fraudulent tradelines within four business days.
Step 3: Issue an FCRA Notice of Fraudulent Account
Send copies of your police report, FTC affidavit, and home IP address verification to the fraud departments of Equifax, Experian, and TransUnion, as well as Sunlight Financial and Cross River Bank. Direct them to cease reporting the fraudulent loan immediately.
Step 4: Demand Arbitration with Fee-Shifting
If Sunlight Financial refuses to release the fraudulent account voluntarily, consumer counsel can initiate individual arbitration before the American Arbitration Association (AAA). Under state consumer-fraud statutes (such as California's CLRA, Florida's FDUTPA, Texas DTPA, or New Jersey CFA), victims of predatory signature schemes can recover actual damages, emotional distress damages, statutory civil penalties, and full attorney’s fees paid by the lender.
Verbatim Demand Template: DocuSign Certificate of Completion & IP Audit Demand
Copy and transmit via USPS Certified Mail and email to Sunlight Financial's Fraud & Legal Compliance Desk.
[Date]

VIA CERTIFIED MAIL (RETURN RECEIPT REQUESTED) & ELECTRONIC TRANSMISSION
To: Sunlight Financial LLC / Special Investigations & Fraud Division
    [Current Servicing Address from Statements]
    Email: <!--email_off-->[email protected]<!--/email_off--> / <!--email_off-->[email protected]<!--/email_off-->
Copy: Cross River Bank
      c/o Consumer Lending Fraud & Risk Management
      885 Teaneck Road, Teaneck, NJ 07666

RE: FORMAL DEMAND FOR DOCUSIGN CERTIFICATE OF COMPLETION & ENVELOPE AUDIT TRAIL
    NOTICE OF FRAUD IN THE FACTUM UNDER UCC § 3-305(a)(1)
    IDENTITY THEFT NOTIFICATION UNDER FCRA SECTION 605B (15 U.S.C. § 1681c-2)
    Alleged Borrower: [Your Full Name]
    Property Address: [Your Residential Address]
    Alleged Loan Account #: [Loan Account Number]
    Partner Solar Installer: [Solar Installation Company Name]
    Sales Representative Name (if known): [Sales Rep Name]

Dear Fraud Investigations & Legal Compliance.

I am writing to formally dispute the validity of the promissory note and consumer credit transaction referenced above.

I DID NOT EXECUTE, AUTHORIZE, OR CONSENT TO THE SIGNING OF THIS FINANCING AGREEMENT. MY DIGITAL SIGNATURE WAS FORGED OR PROCURED THROUGH FRAUD IN THE FACTUM BY REPRESENTATIVES OF [INSTALLER NAME].

Under Uniform Commercial Code § 3-305(a)(1), an instrument procured through fraud that induced the obligor to sign the instrument without knowledge or reasonable opportunity to learn of its character or essential terms is VOID AB INITIO and unenforceable by any holder.

MANDATORY DOCUMENT PRODUCTION DEMAND.
To conduct a complete forensic audit of the electronic execution of this alleged agreement, demand is hereby made pursuant to state consumer fraud statutes and federal lending disclosure regulations that Sunlight Financial deliver within fifteen (15) calendar days:

1. The complete, unredacted PDF of the alleged Promissory Note, Disclosure Packet, and Installation Agreement.
2. The complete, multi-page DocuSign (or Adobe Sign) CERTIFICATE OF COMPLETION, including:
   - Full Envelope ID and historical transaction log.
   - The recipient delivery email address and delivery timestamp.
   - The signing IP address (IPv4 / IPv6) and geolocation metadata.
   - The browser user-agent string, device fingerprint, and operating system.
   - Exact timestamps down to the second for "Envelope Viewed" and "Envelope Signed."
3. Proof of Signer Identity Authentication: Copies of any SMS verification logs, phone numbers used for two-factor authentication, or knowledge-based authentication (KBA) question answers.

PRESERVATION OF EVIDENCE & IMMEDIATE ACCOUNT FREEZE:
1. You are directed to immediately place this account into FROZEN / DISPUTED FRAUD STATUS and cease all automatic ACH payment drafting and collection demands.
2. Under Section 605B of the Fair Credit Reporting Act (15 U.S.C. § 1681c-2), you are prohibited from submitting adverse or delinquent tradeline reporting to Equifax, Experian, or TransUnion pending resolution of this fraud investigation.
3. You are placed on formal legal notice to preserve all server logs, email dispatches, IP transmission records, and communications between Sunlight Financial and [Installer Name] concerning this transaction.

Provide the requested forensic audit trail directly to me via email at [Your Email Address] and by mail at the address below.

Sincerely,

_________________________________________
[Your Signature]
[Your Printed Name]
[Your Phone Number]
[Your Mailing Address]
FAQ
What if I initialed the sales rep's tablet but didn't know it was a loan?
Procuring customer initials on sales tablets without disclosing loan terms constitutes fraud in the factum. If the representative told you that you were merely signing to "confirm a roof inspection" or "receive a free quote," but secretly attached your digital initials to a 25-year financing note, there was no mutual assent. The agreement is legally invalid.
Can Sunlight Financial hold me responsible if their partner installer committed the forgery?
No. Under the federal FTC Holder Rule (16 C.F.R. § 433.2), Sunlight Financial and Cross River Bank are legally subject to all claims and defenses that you could assert against the seller. A lender cannot enforce a promissory note that their chosen vendor procured through forgery and criminal deception.
How do I prove my home IP address was different from the signing IP address?
Log into your home Wi-Fi router or request your historical IP connection logs from your internet service provider (ISP). You can also provide home utility bills and cell phone billing records demonstrating your geographic location at the exact timestamp recorded on the DocuSign certificate.
Will Sunlight Financial delete the account from my credit report?
Once formal proof of forgery is established (such as an FTC Identity Theft Report and an audit trail showing an IP/email mismatch), Sunlight Financial and Cross River Bank have a mandatory legal obligation under the Fair Credit Reporting Act to delete the tradeline entirely. Failure to do so exposes the lender to federal statutory damages under 15 U.S.C. § 1681n.
Sources
- Federal Trade Commission: Identity Theft Reporting & Victim Recovery Procedures, IdentityTheft.gov.
- Uniform Commercial Code: UCC § 3-305 - Defenses and Claims in Recoupment (Fraud in the Factum), Legal Information Institute, Cornell Law School.
- Electronic Signatures in Global and National Commerce Act (E-SIGN Act): 15 U.S.C. § 7001 et seq., FTC Regulatory Review.
- Connecticut Attorney General William Tong: Enforcement Action Against Vision Solar for Forged Contracts and Unfair Practices, CT Attorney General.
- Consumer Defense Arbitration Docket: Arbitration Award Voiding $113,000 Solar Promissory Note for Electronic Forgery & Elder Exploitation (2026).
Next Research Steps
Use these resources to connect this issue with the broader solar scam pattern, the relevant legal framework, and the next practical action.
Solar panel scams
Start with the main solar panel scams guide for the broad definition and recovery roadmap.
Solar financing fraud compensation
Use this guide for loan, dealer-fee, payment-jump, PACE, lease, and lender-defense issues.
Solar panel scams and ripoffs
Compare scam patterns, red flags, door-to-door pressure, fake rebates, and impersonation tactics.
Homeowner legal rights
Review cancellation, rescission, UDAP, TILA, Holder Rule, arbitration, and lawsuit options.
Trapped in a predatory loan?
FTC Holder Rule & cancellation rights