Remove Sunlight Financial UCC-1 Lien [Letter Template]
Step-by-step guide and copyable legal demand letter to remove or subordinate a Sunlight Financial UCC-1 fixture filing from your county property records.
Disclaimer: This guide provides educational analysis regarding Uniform Commercial Code (UCC) fixture filings and title issues. It does not constitute legal or escrow advice. Always consult an attorney or your closing title officer when resolving real estate title clouds.
Direct Answer To remove a Sunlight Financial UCC-1 fixture filing from your property title, you must obtain and file a UCC-3 Financing Statement Amendment (Termination) with your county recorder or secretary of state. If you are refinancing your mortgage or selling your home, Sunlight Financial and originating lenders like Cross River Bank can be required to execute an emergency subordination agreement to permit mortgage funding, or issue an immediate UCC-3 termination under Uniform Commercial Code § 9-513 if the underlying contract was voided, paid off, or rescinded due to fraud.
The Title Shock: "The Sales Rep Swore There Was No Lien on My House"
One of the most common deceptions in residential solar sales is the rep's confident pitch at the kitchen table.
"This is just a simple unsecured equipment loan. No lien will ever be placed on your home, and your title remains 100% clean."
Homeowners believe them—until three, five, or seven years later when they attempt to refinance their mortgage or sell their house. Suddenly, the closing officer or mortgage underwriter calls in a panic.
"There is a Uniform Commercial Code (UCC-1) fixture filing recorded against your real property by Sunlight Financial and Cross River Bank. The buyer's mortgage underwriter refuses to close until this cloud on title is cleared or subordinated."
In Ohio, a homeowner attempting to refinance their mortgage discovered a UCC-1 filing indexed against their parcel by Sunlight Financial. The underwriter refused to fund unless Sunlight subordinated the lien. Sunlight’s subordination department demanded a $250 administrative fee, certified inspection reports, and a 30-day review period. By the time Sunlight processed the paperwork, the homeowner’s 60-day mortgage rate lock had expired, costing them thousands of dollars in higher monthly mortgage payments.
What Is a UCC-1 Fixture Filing and How Does It Affect Real Estate?
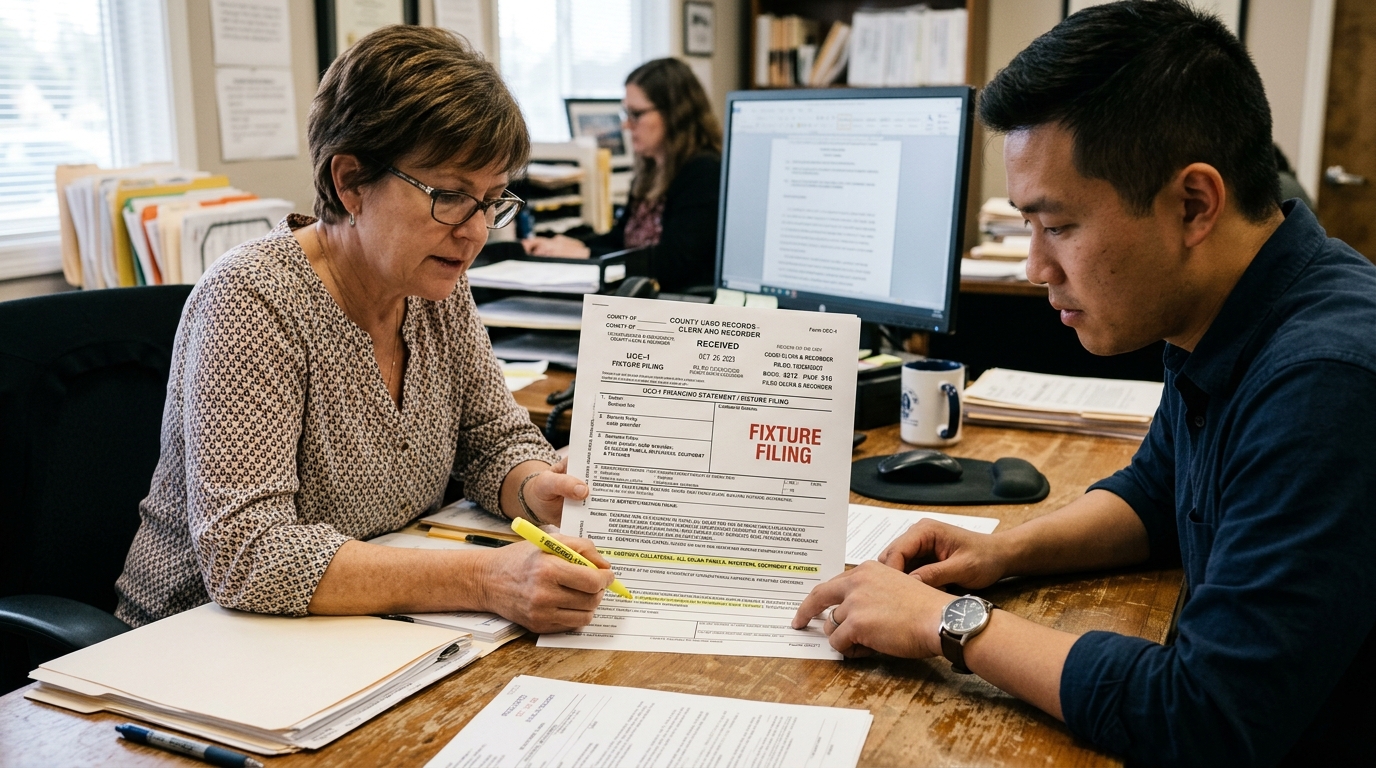
Under Article 9 of the Uniform Commercial Code, a UCC-1 Financing Statement gives a creditor a perfected security interest in personal property. Because solar panels and inverters are attached to your roof and wired into your main electrical panel, state law classifies them as "fixtures"—personal property so connected to real estate that an interest in them arises under real property law.
When Sunlight Financial originates a loan through Cross River Bank, they record a fixture filing in the county recorder's office (or registry of deeds) where your home is located.
Why Mortgage Underwriters Panic Over UCC-1 Filings
- Lien Priority Concerns: First-mortgage lenders (Fannie Mae, Freddie Mac, FHA, VA) require that their deed of trust or mortgage hold first-lien priority. While a UCC fixture filing theoretically attaches only to the solar hardware, county recording systems index fixture filings against the real property parcel itself.
- Title Inability to Convey Free and Clear: A buyer’s title insurance company cannot issue a clear title policy with an unreleased creditor filing sitting on the parcel index.
- Foreclosure Complications: In the event of a mortgage default, lenders fear that the solar creditor could assert superior rights over equipment physically integrated into the residence.
Two Paths to Clear Your Title: Subordination vs. Termination
Depending on whether you intend to keep the solar loan or eliminate it entirely, there are two distinct legal mechanisms to resolve a Sunlight Financial fixture filing.
graph TD
    A[UCC-1 Fixture Filing on Title] --> B{What is your objective?}
    B -->|Refinancing & Keeping Loan| C[Lien Subordination]
    B -->|Selling Home or Voiding Fraudulent Loan| D[UCC-3 Termination]

    C --> E[Submit Subordination Packet to Sunlight Servicer]
    E --> F[Sunlight Subordinates Priority to New First Mortgage]
    F --> G[Underwriter Closes Refinance]

    D --> H[Demand UCC-3 Termination under UCC § 9-513]
    H --> I[Lender Records UCC-3 Termination Statement]
    I --> J[Lien Extinguished from County Parcel Index]
Path 1: Emergency Lien Subordination (For Refinances)
If you are refinancing your existing home loan and plan to continue paying Sunlight Financial, you do not need the loan cancelled—you need Sunlight to subordinate its security interest:
- How It Works: Sunlight Financial executes a formal Subordination Agreement stating that its fixture filing is subordinate and junior to the new first mortgage.
- The Process: Request a Subordination Package from Sunlight’s escrow/title department immediately upon opening loan application. Expect them to require:
- Title company contact details and escrow file number.
- New lender’s name and exact legal entity name.
- Current payoff or status statement showing the solar account is current.
- Payment of a subordination processing fee (typically $150–$350).
- Pro Tip: Standard processing times range from 15 to 30 business days. Instruct your closing officer to mark the request "CLOSING IMMINENT / RATE LOCK AT RISK" to escalate to a supervisor.
Path 2: Demanding UCC-3 Termination under UCC § 9-513
If your solar loan was paid off, settled, or determined to be void due to installer fraud or signature forgery, Sunlight Financial has an affirmative statutory duty to extinguish the lien immediately.
Under Uniform Commercial Code § 9-513(c), within 20 days after a secured party receives an authenticated demand from the debtor when there is no outstanding secured obligation, the secured party must send a UCC-3 termination statement to the debtor or file the termination statement in the recording office.
If Sunlight Financial fails to file the termination statement within the statutory 20-day window, UCC § 9-625 permits the homeowner to recover statutory damages of $500 plus any actual economic loss suffered (such as a canceled real estate sale or expired mortgage commitment).
What If Your Installer Is Bankrupt and the System Never Worked?
If your system was installed by a defunct contractor like Vision Solar or Pink Energy and never achieved utility Permission to Operate (PTO), Sunlight Financial has no equitable right to maintain a lien on your property.
Under the FTC Holder Rule and state consumer protection laws:
- The failure to provide a functioning, code-compliant solar energy system constitutes a total failure of consideration.
- An invalid underlying promissory note cannot support a perfected security interest.
- Consumer counsel can initiate an American Arbitration Association (AAA) arbitration demand seeking an award ordering Sunlight Financial and Cross River Bank to immediately release all recorded fixture filings and pay title-clearing damages.
In multiple recent consumer arbitrations—including a documented 2026 arbitration award—arbitrators ordered Sunlight Financial not only to void six-figure notes, but specifically mandated that Sunlight execute and record UCC-3 termination statements within 10 days of the award.
Step-by-Step Guide to Demanding Lien Release
If a Sunlight Financial UCC-1 filing is clouding your title, follow these steps immediately:
- Pull the Recorded Instrument: Go to your county recorder’s online public records or visit the courthouse. Download the exact UCC-1 filing document. Note the recording date, instrument number, debtor name, and secured party of record (typically Sunlight Financial LLC or Cross River Bank).
- Determine Underlying Account Status:
- If the loan is being paid off through sale proceeds: Request an official Demand for Payoff from Sunlight. Ensure the payoff letter explicitly states that upon receipt of funds, Sunlight will deliver a signed UCC-3 Termination Statement within 10 business days.
- If the loan is disputed for fraud/insolvency: Issue a formal legal demand letter citing UCC § 9-513, attaching inspection failure reports and PTO denials.
- Escalate to Title Legal Counsel: Have your title insurance underwriter issue a formal notice to Sunlight's legal compliance department. Title companies have dedicated lender-clearance hotlines that bypass retail customer service desks.
- Self-Help Filing (Where Permitted): In states that have enacted revised UCC Article 9, if a creditor fails to record a termination statement after proper 20-day notice, the debtor may file a statement of termination if the filing office allows authenticated debtor-filed UCC-3 statements.
Verbatim Demand Template: 20-Day Formal Demand for UCC-3 Termination (UCC § 9-513)
Copy, complete the fields, and transmit via USPS Certified Mail and email to Sunlight's Title & Collateral Management Desk.
[Date]

VIA CERTIFIED MAIL (RETURN RECEIPT REQUESTED) & ELECTRONIC TRANSMISSION
To: Sunlight Financial LLC / Collateral Management & Title Services
    [Current Servicing Address from Billing Statement]
    Email: [Sunlight Title / Payoff Email]
Copy: Cross River Bank
      c/o Legal & Collateral Control Division
      885 Teaneck Road, Teaneck, NJ 07666

RE: AUTHENTICATED DEMAND FOR UCC-3 TERMINATION STATEMENT PURSUANT TO UCC § 9-513
    NOTICE OF POTENTIAL STATUTORY AND ACTUAL DAMAGES UNDER UCC § 9-625
    Debtor Name(s): [Your Full Name(s)]
    Property / Parcel Address: [Your Property Address]
    County of Recordation: [County Name, State]
    UCC-1 Initial Financing Statement Instrument / Document #: [Recording #]
    Recording Date: [Date Recorded on Title]
    Secured Party of Record: Sunlight Financial LLC / Cross River Bank
    Loan Reference #: [Your Loan Account #]

Dear Collateral Management & Legal Compliance Officer.

This letter constitutes an AUTHENTICATED WRITTEN DEMAND pursuant to Section 9-513 of the Uniform Commercial Code (as enacted in [State Name], [State Statute Citation, e.g., Cal. Com. Code § 9513 / Tex. Bus. & Com. Code § 9.513 / Fla. Stat. § 679.513]).

I am the owner of the real property referenced above and the named debtor on the UCC-1 fixture filing recorded by your institution on [Recording Date] as Instrument #[Recording #] in [County Name] public records.

PLEASE TAKE NOTICE THAT:
1. Absence of Outstanding Secured Obligation: [Select applicable basis.
   Option A: The underlying promissory note has been paid in full / satisfied in full as of [Date].
   Option B: The underlying contract is void ab initio due to documented signature forgery / fraud in the factum under UCC § 3-305(a)(1).
   Option C: The underlying contract has been formally rescinded and extinguished pursuant to the FTC Holder Rule (16 C.F.R. § 433.2) following total commercial abandonment and bankruptcy liquidation of the merchant seller, [Installer Name].]
2. Statutory 20-Day Window: Pursuant to UCC § 9-513(c), within TWENTY (20) CALENDAR DAYS after receipt of this authenticated demand, the secured party MUST send to the debtor or cause to be filed in the relevant filing office an official UCC-3 Termination Statement that identifies the initial financing statement by file number and states that the filing has ceased to be effective.

STATUTORY WARNING UNDER UCC § 9-625.
Be advised that if you fail to file or deliver the UCC-3 Termination Statement within the mandatory 20-day statutory period, UCC § 9-625 explicitly entitles the debtor to recover.
a) Statutory damages of $500.00; AND
b) Any actual economic damages caused by your failure to comply, including but not limited to lost property sale proceeds, escrow extension penalties, higher mortgage interest charges caused by expired rate locks, and title clearing fees.

A real estate conveyance / mortgage refinance transaction is currently pending on this parcel with closing scheduled for [Closing Date, if applicable]. Time is strictly of the essence.

Deliver the executed UCC-3 Termination Statement or official recording confirmation directly to the undersigned at [Your Email Address] and to Escrow Officer [Escrow Officer Name, Email, Title Company] within 20 days.

Sincerely,

_________________________________________
[Your Signature]
[Your Printed Name]
[Your Phone Number]
[Your Mailing Address]
FAQ
Can Sunlight Financial foreclose on my house if I default on my loan?
No. A UCC-1 fixture filing is not a mortgage or a deed of trust. Sunlight Financial does not hold a security deed to your real estate parcel. They cannot initiate judicial or non-judicial mortgage foreclosure to take your home. Their security interest is restricted strictly to the solar equipment itself.
Why does a fixture filing show up on my property deed if it’s only on the panels?
Because fixtures are physically bolted to real estate, county recording statutes require fixture filings to be recorded in the county land records alongside deeds and mortgages so prospective real estate purchasers have notice of personal property encumbrances.
How much does it cost to subordinate a Sunlight Financial solar loan?
Sunlight Financial typically assesses an administrative fee between $150 and $300 to process a mortgage subordination packet. If you are disputing the loan for fraud or failure of consideration, legal counsel can demand that Sunlight waive this fee as part of an escrow resolution.
How long does Sunlight Financial take to file a UCC-3 termination?
Standard turnaround times for Sunlight to process and record a UCC-3 termination statement are 2 to 4 weeks. Under UCC § 9-513, they must act within 20 calendar days of receiving an authenticated written demand once the obligation is satisfied or voided.
Sources
- Uniform Commercial Code: UCC § 9-513 - Termination Statement, Legal Information Institute, Cornell Law School.
- Uniform Commercial Code: UCC § 9-625 - Remedies for Secured Party's Failure to Comply with Article, Cornell Law School.
- Consumer Financial Protection Bureau: CFPB Supervisory Highlights: Deceptive Practices in Residential Solar and Fixture Lending, Consumer Financial Protection Bureau.
- American Arbitration Association: Consumer Arbitration Rules & Fee Schedules, AAA Consumer Rules.
- Minnesota Attorney General: State of Minnesota v. GoodLeap, Sunlight Financial, Cross River Bank et al., Hennepin County District Court File No. 27-CV-24-3482.
Next Research Steps
Use these resources to connect this issue with the broader solar scam pattern, the relevant legal framework, and the next practical action.
Solar panel scams
Start with the main solar panel scams guide for the broad definition and recovery roadmap.
Solar financing fraud compensation
Use this guide for loan, dealer-fee, payment-jump, PACE, lease, and lender-defense issues.
Homeowner legal rights
Review cancellation, rescission, UDAP, TILA, Holder Rule, arbitration, and lawsuit options.
Trapped in a predatory loan?
FTC Holder Rule & cancellation rights