Sunrun Lease Buyout Before Selling Your Home [Escrow Action Plan]
Selling a home with a Sunrun solar lease? Learn how Sunrun calculates buyouts, how to overcome UCC-1 lien closing delays, and avoid escrow collapse.
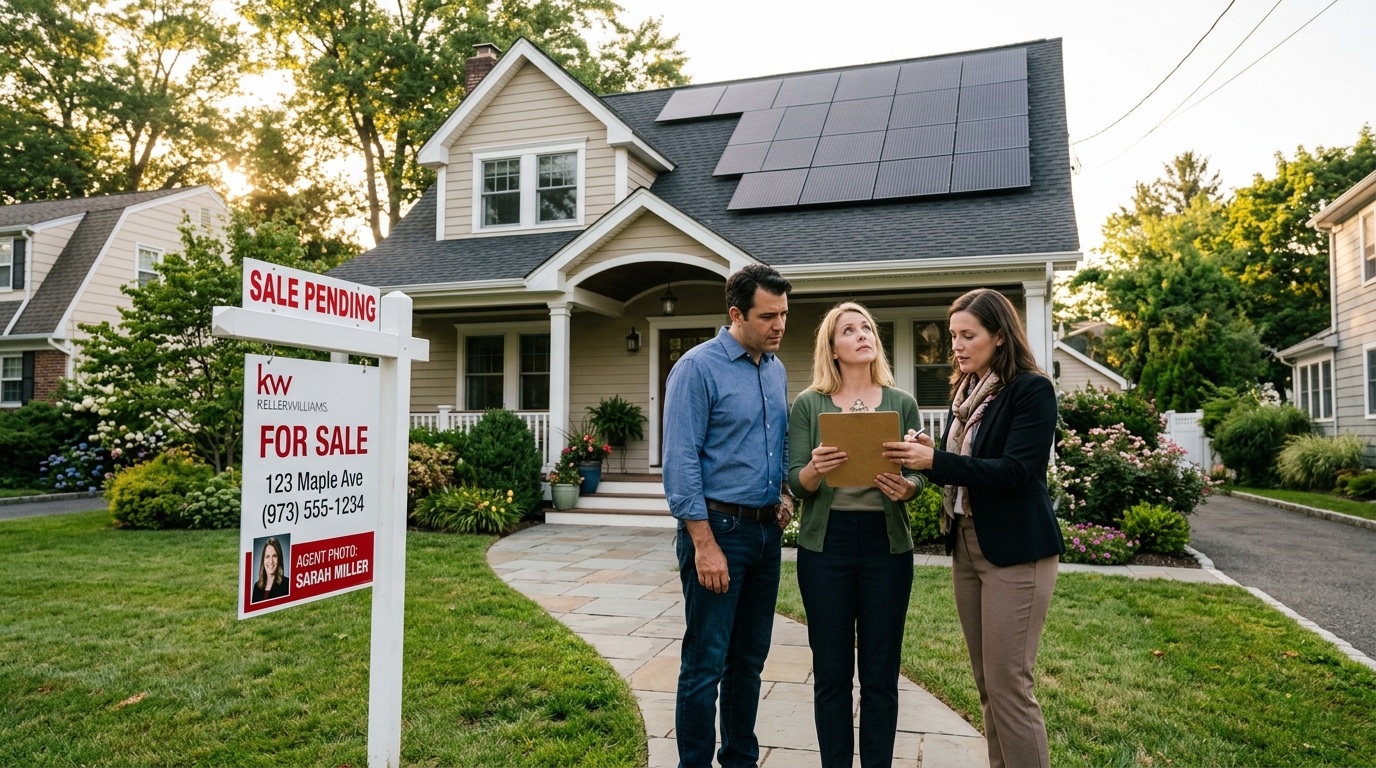
Nothing derails a residential real estate closing faster than an uncooperative solar company. When selling a home with a Sunrun solar lease or Power Purchase Agreement (PPA), homeowners routinely discover that prospective buyers refuse to assume 20- to 25-year contracts burdened by 2.9% annual payment escalators. (See our guide on how to challenge escalator clauses in solar leases and our escrow closing checklist for solar leases).
When the seller requests a payoff quote to clear title before closing, Sunrun's response is often an eye-popping buyout demand—frequently ranging from $25,000 to over $55,000—backed by a recorded UCC-1 fixture lien that prevents title insurance from issuing until Sunrun gets paid. If roof repairs are simultaneously required, review our breakdown on Sunrun solar panel removal for roof replacement.
Disclaimer This guide provides objective consumer information, real estate escalation protocols, and commercial code options. It does not constitute formal legal or real estate advice. If a disputed fixture lien threatens to breach a purchase and sale agreement, consult a licensed real estate attorney or consumer protection lawyer immediately.
1. How Sunrun Calculates a Lease Buyout Price
Homeowners frequently assume that buying out their solar lease resembles paying off a car loan or mortgage, where the balance reflects the wholesale cost of the hardware minus depreciation. With Sunrun, that assumption is dead wrong.
Sunrun calculates lease buyouts using one of two formulas specified in its standard contract terms.
| Valuation Method | How Sunrun Calculates It | Practical Cost to Seller |
|---|---|---|
| Net Present Value (NPV) of Remaining Payments | Sum of all future monthly payments through year 20 or 25, including compounding annual escalators (typically 2.9%), discounted to present value using an internal discount rate (often 5% to 7%). | Extremely high. For a lease in Year 5 with 20 years remaining, this calculation regularly yields $28,000–$50,000+. |
| Fair Market Value (FMV) Appraisal | An independent or internal appraisal of the system's value installed on the roof. Sunrun often requires the homeowner to pay for a certified appraisal. | Unpredictable. Appraisers hired through solar company networks frequently value older panels near replacement cost rather than salvage value. |
Under most Sunrun agreements, the contract stipulates that the buyout price is the higher of the NPV of remaining payments or Fair Market Value. This formula ensures Sunrun captures virtually the entire stream of anticipated future revenue, effectively penalizing the homeowner for early termination.
2. When Sunrun Holds Closing Hostage: The $27,300 Precedent
The friction between solar leases and home sales is not hypothetical; it has been documented at the national investigative level. A landmark Bloomberg investigative report highlighted the exact scenario confronting thousands of home sellers: Sunrun blocked the closing of a residential property sale by refusing to remove its UCC fixture filing until the sellers wired a $27,300 buyout fee directly from their closing proceeds.
Why does this happen?
- The Title Cloud When Sunrun installs panels, it records a UCC-1 Financing Statement in county land records against the fixtures. Mortgage lenders (Fannie Mae, Freddie Mac, FHA) require first-lien priority; they will not fund a buyer's loan while an uncoordinated solar fixture filing remains of record.
- Artificial Timing Crises Sunrun’s transfer and payoff department operates with severe administrative backlogs. While escrow operates on rigid 30- to 45-day timelines, Sunrun often takes 3 to 6 weeks merely to generate a formal payoff statement.
- The Escrow Squeeze With the buyer threatening to walk away and retain their earnest money deposit, sellers feel coerced into signing predatory payoff agreements just to close the transaction.
                     The Escrow Solar Trap Timeline
                                   │
      ┌────────────────────────────┼────────────────────────────┐
      ▼                            ▼                            ▼
   Day 1–10                     Day 15–25                    Day 30–45
Buyer Rejects Lease         Sunrun Payoff Stall         Title Company Freeze
Buyer's lender refuses to   Sunrun takes 3-4 weeks to   UCC-1 lien blocks clean
approve 2.9% PPA escalator; issue payoff demand; quotes title; seller forced into
demands seller buy out panels  inflated $30k+ buyout    unfavorable wire payoff
3. Buyout vs. Transfer: Evaluating Your Options
Before wiring tens of thousands of dollars to Sunrun, evaluate whether a transfer or escrow workaround is viable.
Option A: Formal Lease Transfer to Buyer
If the buyer agrees to assume the lease, Sunrun requires the buyer to pass a proprietary soft credit check (typically requiring a 650+ FICO score) and execute a formal Assignment and Assumption Agreement.
- The Risk Sunrun frequently takes 30+ days to process credit approvals. If Sunrun’s transfer portal stalls, the closing date may expire before the transfer completes.
Option B: Prepaying the Remaining Payments (Without Buying Hardware)
Some Sunrun contracts allow the seller to "prepay" all remaining monthly lease payments while leaving ownership of the panels with Sunrun. The buyer gets free solar electricity for the remaining lease term without assuming monthly payment obligations.
- Advantage Often costs $3,000 to $8,000 less than a full equipment buyout because the seller does not purchase the depreciated hardware.
Option C: Escrow Holdback Agreement
If Sunrun cannot deliver a payoff statement or UCC-3 termination in time for closing, ask the title company and buyer's lender whether an escrow holdback is permissible. The title company holds 1.5x the estimated payoff amount (e.g., $45,000) in escrow from seller proceeds, allowing the deed to record while negotiations with Sunrun continue post-closing.
4. Step-by-Step Sellers' Escalation Checklist
If your closing date is approaching and Sunrun is delaying your payoff or transfer, execute this emergency protocol.
Step 1: Request an Itemized Payoff Statement in Writing (Day 1)
Do not request payoffs by telephone. Submit a formal request via Sunrun’s online customer portal and via email to [email protected] and [email protected]. Demand an itemized statement detailing:
- The exact discount rate applied to calculate Net Present Value;
- The remaining balance of hardware depreciation;
- Written confirmation that a UCC-3 Financing Statement Amendment (Termination) will be delivered to escrow within 5 business days of payoff receipt.
Step 2: Involve Your Real Estate Attorney and Title Officer
Inform your settlement agent immediately. Instruct the title company to send a formal Demand for Payoff Statement on title company letterhead directly to Sunrun's legal department in San Francisco. Institutional demands carry significantly greater weight than individual homeowner phone calls.
Step 3: Pay Under Protest with Reservation of Rights (If Forced to Close)
If you must wire funds to Sunrun to prevent a purchase contract breach, do not sign an unconditional release of claims. Have your attorney ensure that the payoff cover letter explicitly states.
"Payment is remitted under economic duress, under protest, and with full reservation of all rights and claims regarding deceptive trade practices, unconscionable contract terms, and statutory damages under state law."
Step 4: Enforce UCC § 9-513 Lien Termination Deadlines
Under Uniform Commercial Code § 9-513(c), once a secured obligation has been fully satisfied, the secured party has 20 days after receiving an authenticated demand to file a UCC-3 termination statement. If Sunrun fails to release the lien within the statutory deadline, it is liable for actual damages and statutory penalties under UCC § 9-625.
Sources and Official References
- Uniform Commercial Code § 9-513 (Termination Statement) — Statutory rules governing mandatory termination of UCC financing statements upon debt satisfaction.
- Uniform Commercial Code § 9-625 (Remedies for Secured Party's Failure to Comply) — Statutory damages for improper lien retention.
- Fannie Mae Selling Guide: Solar Panels (B2-3-04) — Official underwriting standards for properties with leased solar panels and UCC fixture filings.
- FTC Guidance on Solar Financing & Real Estate Transfers — Federal consumer advisory regarding title clouds and solar lease assumptions.
FAQ
Can I sell my house with a Sunrun lease without buying it out?
Yes. If your buyer is willing to take over the contract and meets Sunrun's credit qualifications (generally a 650+ credit score), you can execute a lease transfer. However, in competitive real estate markets, many buyers refuse to assume leases with compounding 2.9% escalators, forcing sellers to negotiate a buyout.
How long does a Sunrun lease transfer take to complete?
Sunrun's stated timeline is 2 to 4 weeks, but consumer complaint records show transfers routinely take 6 to 10 weeks due to administrative delays, credit verification backlogs, and lost paperwork. Home sellers should initiate the transfer process the moment their home is listed on the MLS.
What is a solar UCC-1 fixture filing and why does it block closing?
A UCC-1 fixture filing is a public legal notice filed in county land records establishing that Sunrun owns the solar equipment installed on your roof. Because mortgage lenders require first-lien priority on the real property, title insurance companies will not issue a clean title policy until the UCC filing is either subordinated or terminated via a UCC-3 filing.
Can Sunrun charge a transfer fee to the home seller or buyer?
Review your specific agreement. Many older Sunrun and Vivint Solar contracts do not permit administrative transfer fees, while newer contracts may attempt to charge a $250 to $500 processing fee. If your contract does not explicitly authorize a transfer fee, dispute the charge in writing before closing.
Next Research Steps
Use these resources to connect this issue with the broader solar scam pattern, the relevant legal framework, and the next practical action.
Solar panel scams
Start with the main solar panel scams guide for the broad definition and recovery roadmap.
Solar financing fraud compensation
Use this guide for loan, dealer-fee, payment-jump, PACE, lease, and lender-defense issues.
Solar company complaint directory
Look up installers, lenders, bankruptcies, warranty problems, and customer-service complaint patterns.
Solar fraud by state
Compare state and city issues against the national solar fraud map.
Disputing Sunrun terms?
Contract cancellation & warranty remedies