The Solar Syndicate Trap: Dealer-Lender Liability & Debt Cancellation [Legal Guide]
How multi-tiered solar syndicates use super-dealers, shell contractors, and lenders like Sunlight Financial and EnFin to trap homeowners—and the legal roadmap to cancel the debt.
Disclaimer: This article provides factual consumer education, public docket analysis, and regulatory reporting. It does not constitute formal legal advice. If you suspect your signature was forged, loan terms were misrepresented, or your contractor abandoned your project, consult a licensed consumer-protection attorney in your state.
Overview
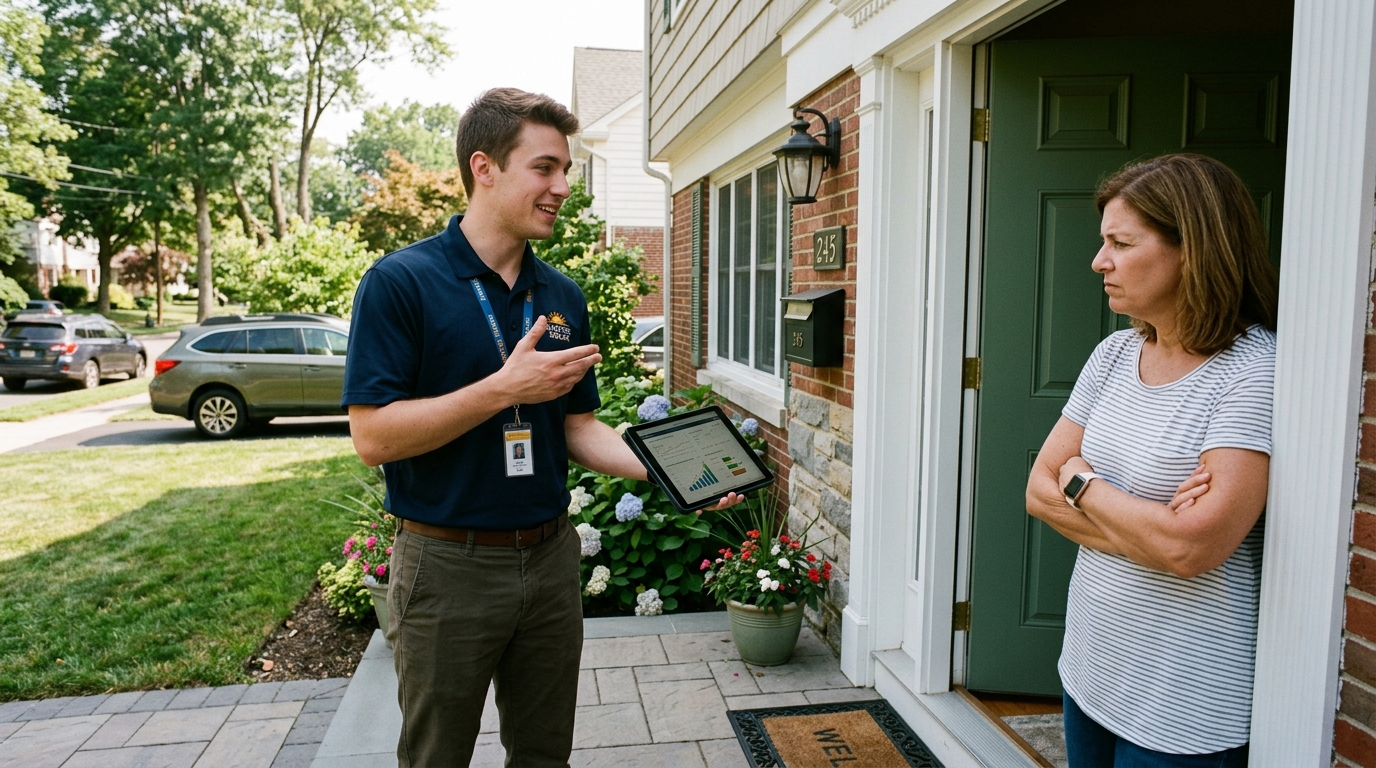
When a residential solar salesperson sits down at your kitchen table, the presentation feels seamless. The representative wears a polo shirt featuring a recognized brand, displays sleek utility bill calculation tools on an iPad, and promises immediate monthly utility savings backed by a federal "clean energy rebate."
In reality, the homeowner is not entering into an agreement with a single unified business. They are being drawn into a coordinated, multi-tiered commercial syndicate specifically structured to extract upfront financing disbursements while distributing legal liability across isolated corporate veils.
When the solar array underperforms, utility bills increase rather than disappear, or the installing contractor ghosts the homeowner, each corporate entity points to the next:
- The sales dealer claims they merely provided marketing and that installation quality is the contractor's responsibility.
- The installing contractor claims they simply mounted the hardware specified by the dealer and have since changed corporate names or entered insolvency.
- The non-bank lender (such as Sunlight Financial, EnFin Corp., GoodLeap, or Solar Mosaic) insists they are an independent financial institution entitled to 25 years of monthly loan payments regardless of whether the rooftop panels generate a single kilowatt-hour.
Homeowners trapped in this web are not helpless. By applying the FTC Holder Rule, uncovering undisclosed dealer fees under federal lending laws, enforcing statutory Home Solicitation cooling-off rights, and utilizing individual arbitration strategies (such as specialized consumer arbitration claims), consumers have established legal pathways to void promissory notes, expunge property liens, and force statutory equipment forfeiture.
1. The Anatomy of a Solar Syndicate
A forensic regulatory review of transactions involving national sales networks, shell installation contractors, and non-bank lending facilities reveals an interconnected distribution chain. The matrix below outlines how these specialized entities divide roles and the governing legal precedents that pierce their liability shields.
| Corporate Role | Target Entity Type | Governing Regulatory Actions & Judicial Precedents | Documented Violations & Fraud Signatures | Concrete Evidentiary Value for Borrowers |
|---|---|---|---|---|
| Direct Sales Broker / Super-Dealer | Sunder Energy, Powur, LGCY Power | Sunder Energy, LLC v. Jackson, 305 A.3d 723 (Del. Ch. 2023), aff'd in part, No. 455, 2023 (Del. Dec. 10, 2024); BBB Docket #90049414 | Judicial finding of executive breach of fiduciary duty; secretly padding contractor prices over actual quotes to extract unearned margins; deceptive utility savings models; DocuSign rushing on vulnerable consumers | Establishes an institutional scheme of price manipulation and bad faith that directly overcomes integration clauses and standard contract waivers |
| EPC Installation Contractor | Regional shell entities (e.g., Heritage Energy Systems, NSIS Solar, Vision Solar) | State AG Consumer Protection dockets; BBB dockets with 100% unanswered complaint rates; local building licensing boards | Operating interchangeable corporate shell entities to evade warranty liabilities; failing to remit promised collateral promotional credits; deploying undersized systems creating severe monthly deficits; post-install communication abandonment; unlawful cancellation fee threats | Direct evidence of failure of consideration, breach of contract, and unpermitted installation work; triggers statutory rescission rights |
| Specialized Non-Bank Lender | EnFin Corp. / Hatch Bank, Sunlight Financial / Cross River Bank, GoodLeap | Active nationwide class investigations (Lieff Cabraser); Minnesota AG $35M dealer fee lawsuit; federal MDL 3128 TILA litigation; CFPB Truth in Lending Act (TILA) scrutiny | Capitalizing undisclosed dealer fees (10% to 40%) into loan principal; deceptive 18-month balloon payment structures tied to non-refundable tax credits; heavily front-loaded interest schedules; predatory UCC-1 fixture filings clouding home titles | Direct assignee liability under the FTC Holder Rule (16 C.F.R. § 433.2); unbundling concealed dealer fees establishes actionable TILA usury and deceptive sales claims |
| Brand Licensor / Lead Anchor | Promotional brand licensors (e.g., ADT Solar / Sunpro Solar) | Massachusetts AG $3.8M Deceptive Sales Settlement (Oct. 2024); Potras v. ADT Solar LLC, No. A-1-CA-40912 (N.M. Ct. App. 2024); Tutson v. Sunpro Solar (C.D. Cal. 2024) | Deceptive marketing of the 30% federal tax credit to homeowners without tax liability; failure to provide statutory cooling-off cancellation notices; autodialed telemarketing violations; drafting unconscionable liability shields attempting to bar treble damages | Corroborates deceptive use of trusted brand equity to induce appointments; appellate precedent in Potras defeats arbitration clauses that attempt to waive statutory treble damages |
| Successor / Asset Consolidator | Complete Solar / SunPower Corp. roll-ups, secondary debt purchasers | Post-Chapter 11 liquidation filings; SEC Form S-1 registration dockets; BBB formal settlement repudiation tracking | Acquiring sales assets while attempting to disclaim consumer liabilities; issuing written settlement offers to aggrieved consumers and subsequently repudiating them upon assumption of operational control | Prevents corporate asset transfers from insulating sales entities against rescission; establishes successor liability under state commercial codes |
2. Shared Deceptions: The Sunlight Financial & EnFin Playbook
While homeowners often believe their dispute is unique to a single company, the operational mechanisms used by Sunlight Financial, EnFin Corp., GoodLeap, and Solar Mosaic rely on identical financial architecture.
A. Concealed Dealer Fees (10% to 40%) Capitalized into Principal
To market artificially low surface interest rates (such as 1.99% or 2.99% APR), solar lenders charge originating dealers an upfront financing surcharge. In standard industry practice, this dealer fee ranges between 10% and 40% of the gross contract value.
Rather than disclosing this surcharge as a finance charge—as mandated by the federal Truth in Lending Act (TILA, 15 U.S.C. § 1605) and Regulation Z (12 C.F.R. § 1026.4)—dealers and lenders quietly roll the fee directly into the capitalized principal balance of the loan. A system with a true cash market price of $30,000 is written up as a $45,000 to $50,000 loan balance.
In State of Minnesota v. GoodLeap, LLC, Sunlight Financial LLC, et al. (March 2024), Minnesota Attorney General Keith Ellison sued major solar lenders, alleging they packed more than $35 million in deceptive, disguised dealer fees into over 5,000 consumer loans. Federal courts presiding over MDL 3128 have affirmed that homeowners state valid claims under TILA when lenders disguise financing costs as inflated cash purchase prices.
B. The 18-Month Tax Credit Re-Amortization Cliff
Solar promissory notes are routinely drafted around the assumption that the homeowner will receive a 30% federal residential clean energy credit under Section 25D of the Internal Revenue Code (26 U.S.C. § 25D) and immediately tender that entire lump sum to the lender within 18 months.
Sales reps frequently assure fixed-income seniors, disabled veterans, and hourly workers: "The government pays for 30% of your system." However, Section 25D is a non-refundable tax credit—it can only offset actual federal income tax liability. Homeowners who owe little or no federal income tax receive $0 from the IRS.
When month 18 passes without a five-figure cash prepayment:
- The loan automatically re-amortizes at month 19.
- The monthly payment jumps permanently by 30% to 50%.
- Because early loan payments are overwhelmingly applied to front-loaded interest, the homeowner owes virtually the entire original principal balance, now compounded over 23 remaining years of escalating debt.
C. UCC-1 Fixture Filings That Cloud Home Titles
Lenders routinely tell prospective borrowers: "This is a personal loan; no lien is placed on your house." Yet immediately upon contract execution, lenders record a UCC-1 Financing Statement in county real property records against the installed fixtures.
When the homeowner subsequently attempts to sell their house, refinance an existing mortgage, or settle an estate, title examiners flag the UCC-1 filing as an encumbrance. Mortgage underwriters routinely halt closings until the homeowner pays off the entire $40,000 to $90,000 solar balance or spends weeks pursuing formal subordination agreements.
   Kitchen Table iPad Pitch ("No Liens, Low APR, Bill Elimination")
                                 │
                                 ▼
   Hidden 10%–40% Dealer Fee Capitalized into Principal (TILA Violation)
                                 │
                                 ▼
   UCC-1 Fixture Statement Recorded in County Land Records (Title Clouded)
                                 │
                                 ▼
   Month 18: No Tax Liability -> No Cash Rebate -> Month 19 Payment Cliff
                                 │
                                 ▼
   Installer Vanishes / Rebrands -> Lender Demands 25 Years of Auto-Debits
3. The Consumer Arbitration Strategy: How Individual Demands Unlock Compensation
Faced with predatory solar contracts, homeowners often assume their only option is joining a federal class action. However, major lenders deliberately draft mandatory binding arbitration clauses (under AAA or JAMS rules) into their promissory notes to prevent class litigation.
Experienced consumer litigation counsel have demonstrated how to turn this defense into significant settlement leverage. Consumer attorneys have established records representing homeowners trapped by predatory lenders, including achieving complete cancellations of six-figure solar loans (such as $113,000 promissory notes), full terminations of recorded UCC property liens, and total recoveries exceeding $170,000.
How does this strategy work?
- Massive Upfront Arbitral Forum Costs for Lenders Under consumer arbitration rules (such as AAA Consumer Arbitration Rules or JAMS Policy on Consumer Arbitrations), consumers pay only a nominal filing fee (typically capped around $250). The lender is legally mandated to pay the remainder of all administrative, case management, and arbitrator fees. An individual arbitration demand can cost the lender $3,000 to $10,000+ in non-refundable forum fees before the merits are even argued.
- Equitable Evaluation of Common-Law Fraud In federal appellate courts, procedural hurdles and narrow statutory definitions often protect lenders (as seen in Migliore v. Vision Solar, where federal vicarious claims faced strict agency pleading barriers). In private arbitration, however, professional arbitrators evaluate mutual assent, common-law fraud in the inducement, unconscionability, and forged digital signatures directly.
- Severe Exposure Under State Unfair Trade Laws In Potras v. ADT Solar LLC, No. A-1-CA-40912 (N.M. Ct. App. July 29, 2024), the New Mexico Court of Appeals reviewed standard solar contracts and established that contractual limitation-of-liability clauses cannot strip consumers of their statutory right to recover treble damages under state unfair trade practices acts. When lenders face individual arbitrations asserting statutory treble damages alongside fee-shifting provisions, their commercial calculation rapidly shifts toward settling the matter through complete debt forgiveness and lien termination.
See our detailed analysis of what solar loan settlements actually recover and how arbitration compares to small-claims options.
4. The Utility Trap: Instantaneous Sub-Meter Netting vs. Promised Savings
A primary misrepresentation in solar syndicate sales is the guarantee of utility bill elimination through traditional net metering. Sales representatives routinely promise 1:1 bill offsets in states where public utility commissions have legally eliminated retail net metering.
A textbook example occurs in Indiana under Senate Bill 309 (codified at Ind. Code § 8-1-40 et seq.), which phased out retail net metering (AES Indiana Rider 9) for all new residential interconnections executed after June 30, 2022. Installations in this territory must interconnect under AES Indiana Rider 16: Excess Distributed Generation (EDG).
Tariff Billing Mechanics: Retail Rate vs. Rider 16 EDG Credit
Standard Residential Grid Purchase Rate (AES Indiana Rate RS).
[==================================================] ~$0.140 to $0.146 per kWh

Excess Distributed Generation Export Credit (Rider 16 EDG).
[=============] ~$0.039 to $0.054 per kWh

Economic Value Destruction on Daytime Solar Outflow.
[--------------------------------------------------] ~65% to 73% Immediate Loss
Under Rider 16 EDG tariffs approved by utility regulators:
- Instantaneous Sub-Meter Netting Energy imports and exports are measured continuously and instantaneously, rather than monthly. Solar energy generated during daylight hours is credited at depressed wholesale rates (
4¢ to 5¢/kWh). Power drawn from the grid during evenings is billed at full retail residential rates (14.6¢/kWh). - The Monthly Deficit Trap Because most systems sold by syndicates lack a battery energy storage system (BESS), the homeowner cannot store midday solar power. The array exports daytime power for a meager credit (often totaling only $15 per month), while the homeowner incurs a monthly solar loan payment of $175 to $250 per month, producing a compounding monthly net financial loss.
Guaranteeing 1:1 net metering or bill elimination in jurisdictions where retail net metering has been legally repealed constitutes an objective, factual misrepresentation under state consumer protection statutes.
5. Three Statutory Nuclear Weapons for Borrowers
When challenging predatory solar debt, homeowners and consumer attorneys rely on three statutory mechanisms.
                    ┌────────────────────────────────────────┐
                    │      Statutory Arsenal for Victims     │
                    └───────────────────┬────────────────────┘
                                        │
         ┌──────────────────────────────┼──────────────────────────────┐
         ▼                              ▼                              ▼
 1. FTC Holder Rule             2. Home Solicitation           3. State UDAP Acts
 (16 C.F.R. § 433.2)            Cooling-Off Laws               (Deceptive Sales)
 • Assignee liability           • Missing 10pt bold notices    • Incurable deceptive acts
 • Erases "holder in due course"• 3-day window never opens     • Treble damages (3x)
 • Note cancellation & refund   • 20-Day Hardware Forfeiture   • Mandatory fee-shifting
1. The FTC Holder Rule (16 C.F.R. § 433.2)
The Federal Trade Commission’s Preservation of Consumers' Claims and Defenses Rule mandates that all consumer credit contracts executed in connection with a sale include an express preservation-of-claims notice.
"Any holder of this consumer credit contract is subject to all claims and defenses which the debtor could assert against the seller of goods or services obtained pursuant hereto..."
Under the FTC Holder Rule, non-bank lenders like Sunlight Financial and EnFin cannot escape liability by claiming they are innocent third parties. If the sales dealer or installing contractor engaged in common-law fraud, forged electronic documents, failed to deliver operational equipment, or violated cooling-off rules, every single claim can be asserted directly against the lender to void the loan balance and demand full restitution of all payments made to date.
2. Home Solicitation Cooling-Off Violations & The 20-Day Forfeiture Rule
Because solar transactions almost always originate through door-to-door canvassing at private residences, they are governed by state Home Solicitation Sales Acts (HSSA) and the FTC Cooling-Off Rule (16 C.F.R. Part 429).
Under statutes like Indiana Code § 24-5-10-9 (and similar provisions across California, Florida, Texas, and Ohio), the supplier is legally required to furnish the buyer with two completed copies of a statutory notice of cancellation printed on a separate document in at least ten-point boldface type.
When sales reps rush homeowners through iPad screens, the required physical cancellation documents are rarely provided. Under statutory law:
- The Cancellation Window Never Commenced The statutory 3-day cooling-off period begins to run only after the required forms are delivered. If never delivered, the homeowner retains an ongoing, unexpired right to cancel the agreement indefinitely.
- Mandatory 10-Day Refund Within 10 business days after receiving written notice of cancellation, the supplier must refund all payments and consideration received.
- Statutory Equipment Forfeiture (e.g., Ind. Code § 24-5-10-13(b)) If the homeowner exercises their right to cancel and has possession of installed equipment, the supplier must demand and remove the hardware within twenty (20) calendar days. If the supplier fails to retake possession within 20 days, the supplier's right to possession is statutorily forfeited, and the solar panels and inverters become the unencumbered personal property of the homeowner without further obligation.
3. State Deceptive Consumer Sales Acts & Statutory Treble Damages
State consumer protection statutes (such as the Indiana Deceptive Consumer Sales Act, Ind. Code § 24-5-0.5; Texas Deceptive Trade Practices Act, Tex. Bus. & Com. Code § 17.41; and Florida FDUTPA, Fla. Stat. § 501.204) provide powerful civil remedies for unfair, unconscionable, or deceptive commercial acts.
When deceptive representations—such as concealing $15,000 dealer fees, quoting obsolete utility tariffs, or fabricating tax credit amounts—are executed as part of an institutional scheme, they constitute "incurable deceptive acts."
Under these statutes:
- Consumers are entitled to recover actual damages or statutory treble damages (3× the total contract amount) upon a finding of willful misconduct. $$\text{Statutory Treble Damages} = 3 \times $45,859.00 = $137,577.00$$
- Prevailing consumers are entitled to an award of reasonable attorney fees and litigation expenses, calculated under the lodestar formula.
6. Actionable Dispute Roadmap: 4 Phases to Resolution
If your household is trapped under an predatory or non-performing solar financing agreement, follow this coordinated four-phase roadmap.
  Phase 1: Notice of Statutory Cancellation & Rescission Demand (HSSA / Cooling-Off)
                                   │
                                   ▼
  Phase 2: FTC Holder Rule Notice of Claims and Defenses to Lender & Servicer
                                   │
                                   ▼
  Phase 3: Formal Regulatory Complaints (CFPB, FTC, State AG Consumer Division)
                                   │
                                   ▼
  Phase 4: JAMS / AAA Individual Arbitration Demand or Civil Litigation (Treble Damages)
Phase 1: Statutory Cancellation & Rescission Demand
Serve a formal Notice of Cancellation and Rescission Demand via certified mail with return receipt requested upon the sales dealer, EPC installation contractor, and lender:
- Cite state Home Solicitation Sales Acts and FTC cooling-off rules, declaring that because mandatory statutory cancellation notices in 10-point bold type were never furnished, the right of cancellation remains open.
- Demand an immediate and unconditional refund of all consideration paid within 10 business days.
- Advise the contractor and lender that failure to demand and remove the rooftop equipment within 20 calendar days triggers permanent statutory forfeiture of the hardware.
Phase 2: Deliver the FTC Holder Rule Notice
Simultaneously send a formal Notice of Claims and Defenses under the FTC Holder Rule (16 C.F.R. § 433.2) to the loan servicer and originating non-bank lender (Sunlight Financial, EnFin, GoodLeap, Hatch Bank, Cross River Bank):
- Document the contractor's fraudulent sales representations, concealed dealer fees, and failure of consideration.
- Demand that the lender immediately place the promissory note into formal dispute status and suspend automated payment withdrawals.
- Instruct the lender to withhold derogatory reporting to credit bureaus and execute a formal UCC-3 Termination Statement to clear your property title.
Phase 3: File Regulatory Complaints
Create an official regulatory record by submitting detailed administrative complaints:
- Consumer Financial Protection Bureau (CFPB) File through the CFPB Complaint Portal against the non-bank lender and originating partner bank citing Truth in Lending Act (TILA) violations for concealed dealer fees and deceptive 18-month balloon structures.
- State Attorney General Consumer Protection Division Submit a complaint detailing deceptive trade practices, unpermitted installations, and contractor abandonment.
- Federal Trade Commission (FTC) Report through ReportFraud.ftc.gov for misleading lead generation, autodialed telemarketing, and deceptive brand licensing practices.
Phase 4: Initiate Individual Arbitration or Civil Action
If the lender and contractor refuse to execute complete loan cancellation and lien releases within 30 days:
- Retain experienced consumer-protection counsel to demand individual arbitration through AAA or JAMS, compelling the lender to advance thousands of dollars in forum administration fees.
- Assert statutory causes of action for deceptive consumer sales practices, unbundling of TILA finance charges, statutory rescission, and action to quiet title against wrongful fixture encumbrances.
- Seek statutory treble damages, restitution of all paid funds, and lodestar attorney fee recovery.
Sources and Official References
- Federal Trade Commission: The Holder Rule (16 CFR Part 433)
- Cornell Law LII: Truth in Lending Act Finance Charges (15 U.S.C. § 1605)
- eCFR: Regulation Z Finance Charge Definition (12 CFR § 1026.4)
- Cornell Law LII: Internal Revenue Code Section 25D Clean Energy Credit (26 U.S.C. § 25D)
- eCFR: FTC Cooling-Off Rule for Door-to-Door Sales (16 CFR Part 429)
- Consumer Financial Protection Bureau: Spotlight on Solar Financing and Dealer Fees
- CFPB Consumer Complaint Portal
- State of Minnesota AG: Lawsuit Against Solar Lenders GoodLeap, Sunlight Financial, Mosaic, and Dividend
- FTC Consumer Alert: Clean Energy Scams and Financing Pitfalls
- American Arbitration Association (AAA) Consumer Arbitration Rules
- National Association of Consumer Advocates (NACA) Attorney Directory
FAQ
Is my solar loan connected to Sunlight Financial even if a different company sold it?
Yes. Sunlight Financial (like EnFin, GoodLeap, and Mosaic) rarely sells solar directly to homeowners. Instead, it operates as an institutional financing conduit that partners with independent dealer networks (such as Sunder Energy, Powur, or LGCY) and EPC installation contractors. While your sales rep may have worn a different company logo, Sunlight Financial may hold your underlying promissory note and recorded UCC-1 fixture filing.
How does the FTC Holder Rule help me get out of a solar loan?
Under the federal FTC Holder Rule (16 C.F.R. § 433.2), any defense or claim you have against your solar seller or installer can be asserted directly against the lender who holds your loan. If your installer lied about energy savings, failed to obtain utility permission to operate, or committed fraud, the lender cannot claim immunity. You can use the installer's misconduct to void the loan balance and seek a full refund of past payments.
What is the 20-day hardware forfeiture rule?
Under many state Home Solicitation Sales Acts (such as Indiana Code § 24-5-10-13), if a door-to-door solar contract is canceled due to the company's failure to provide mandatory statutory cooling-off cancellation forms, the seller must refund all monies within 10 days. If the seller does not demand and remove the installed equipment within 20 calendar days after receiving the cancellation notice, the right to possession is statutorily forfeited, and the solar panels become the homeowner's property free of all liens.
Why do consumer lawyers prefer arbitration over class actions for solar fraud?
In solar financing cases, lenders insert mandatory arbitration clauses into contracts to prevent class actions. However, experienced consumer attorneys leverage this requirement: consumer arbitration rules force the lender to pay $3,000 to $10,000+ in non-refundable forum and arbitrator fees per case. Because individual arbitrators can evaluate common-law fraud and forged documents directly, lenders face immense financial and legal pressure to settle by forgiving the debt and clearing property liens.
Can a solar company charge me a $5,000 cancellation fee if I cancel?
No. If the solar company sold the system through in-person home solicitation and failed to deliver the required statutory cooling-off cancellation forms in bold type, your statutory right of cancellation has never expired. Under state and federal home solicitation laws, imposing punitive cancellation fees or penalties for exercising statutory rescission rights is strictly unlawful.
Next Research Steps
Use these resources to connect this issue with the broader solar scam pattern, the relevant legal framework, and the next practical action.
Solar panel scams
Start with the main solar panel scams guide for the broad definition and recovery roadmap.
Homeowner legal rights
Review cancellation, rescission, UDAP, TILA, Holder Rule, arbitration, and lawsuit options.
Solar financing fraud compensation
Use this guide for loan, dealer-fee, payment-jump, PACE, lease, and lender-defense issues.
Report solar fraud
Build a complaint packet for the FTC, CFPB, state attorney general, licensing board, or counsel.
Trapped in a predatory loan?
FTC Holder Rule & cancellation rights