Forged Initials on a Mosaic Solar Loan: California CLRA 30-Day Demand Guide
What to do if Mosaic paid your contractor without authorization, initials were forged, and the loan hit collections. Step-by-step California CLRA guide.
Disclaimer: This article is informational, legal education, and regulatory analysis. It does not constitute formal legal advice. If you suspect your signature or initials were forged on a solar financing agreement, consult a licensed consumer-protection attorney in California.
Overview
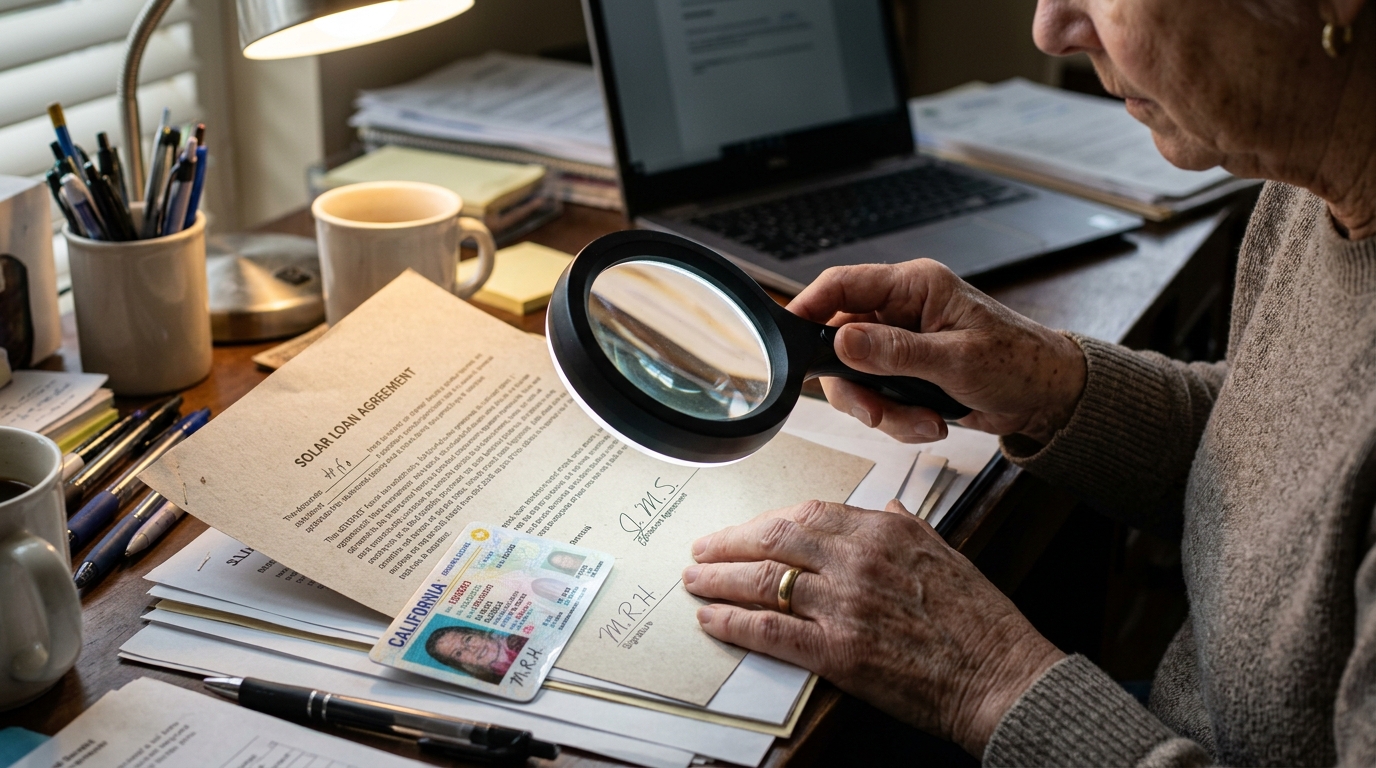
A recurring dispute on California legal forums involves homeowners discovering that solar lender Solar Mosaic LLC (Mosaic) disbursed full loan proceeds to an installer who subsequently abandoned the job, leaving the system non-functional, unpermitted, or completely uninstalled. When homeowners examine their contracts, they frequently discover that change orders, milestone sign-offs, or initial loan disclosures contain initials or digital signatures they never authorized.
Once the contractor disappears with the funds, the lender or third-party collection agencies demand monthly payments, threaten legal action, and report devastating delinquencies to credit bureaus.
California homeowners facing forged initials on a solar loan possess statutory leverage under the California Consumer Legal Remedies Act (CLRA), the Rosenthal Fair Debt Collection Practices Act, the federal FTC Holder Rule, and the Fair Credit Reporting Act (FCRA). By serving a formal 30-day pre-suit CLRA demand, consumers can force lenders to freeze collections, investigate digital signature audit trails, and cancel unauthorized balances. If loan billing commenced prior to final interconnection approval, review our guide on disputing solar loan payments before permission to operate.
Key Points
- Unauthorized Milestone Payouts: Contractors cannot legally trigger milestone disbursements without authorized consumer sign-off, yet sales reps often forge digital initials on electronic completion forms.
- The DocuSign Audit Trail: Digital e-signatures carry IP addresses, timestamps, geolocations, and mobile device identifiers that expose whether an agreement was signed by the borrower or by a sales rep on an iPad.
- California CLRA Statutory Notice (Cal. Civ. Code § 1782): Homeowners must provide a 30-day written demand letter via certified mail. Failure to correct the deceptive practice exposes the lender to actual damages, punitive damages, and mandatory attorney's fees.
- Rosenthal Act & FDCPA Protections: Once notified in writing of an identity theft or forgery dispute, debt collectors must suspend collection activities and provide verification under California law.
- FTC Holder Rule (16 CFR § 433): Mosaic is legally subject to all claims and defenses the borrower could assert against the fraudulent contractor.
The Anatomy of the Forged Milestone Payout
Solar loans are structured around installment disbursements. Under standard lending agreements, Mosaic does not disburse the full $40,000 to $80,000 system cost upfront. Instead, funds are released in phases:
- Milestone 1: Signing and site survey (typically 20–30%).
- Milestone 2: Equipment delivery and mechanical installation (typically 40–50%).
- Milestone 3: Final building inspection and utility Permission to Operate (PTO) (the remaining balance).
[ Predatory Contractor ] ──( Forges Initials on Milestone Doc )──> [ Solar Mosaic Disburses 100% ]
                                                                             │
[ Homeowner Left With Unfinished Panels & $50k Balance ] <────────────────────┘
                               │
                [ Loan Enters Collections & Credit Damaged ]
When a contractor experiences financial distress or runs an outright syndicate scheme, they face cash-flow shortages. To unlock final payouts before inspections or utility interconnection, unscrupulous representatives frequently falsify customer initials on digital milestone completion forms or change orders.
Homeowners only discover the fraud months later when:
- The contractor ghosts calls and leaves wires dangling from the roof.
- The local building department confirms permits were rejected or never closed.
- The utility states no PTO application was ever submitted.
- Mosaic issues payment demands or assigns the note to an aggressive collections agency.
Evidentiary Proof: Cracking the DocuSign Audit Trail
When confronting a lender over forged initials, verbal assertions are insufficient. Financial institutions often respond with boilerplate letters stating: "Our records indicate this contract was electronically signed from your email address."
To defeat this defense, you must request and examine the DocuSign Certificate of Completion or Adobe Sign Audit Report.
Every valid electronic signature platform creates an immutable audit trail capturing forensic metadata.
| Metadata Field | What Legitimate Signing Shows | What Forged / Sales-Rep Signing Shows |
|---|---|---|
| IP Address | Matches homeowner's home broadband router | Matches cellular provider (e.g., T-Mobile/Verizon mobile hotspot used by rep) |
| Geolocation | Coordinates corresponding to the borrower's residence | Coordinates corresponding to the contractor's office or rep's travel path |
| Device & Browser | Borrower's personal computer or private phone | iPadOS / tablet identifier tied to sales software |
| Timestamp Intervals | Realistic reading time between 20–50 contract pages (15–45 minutes) | Rapid-fire automated initialing (less than 60 seconds total) |
| Email Access Hash | Opened via homeowner's private webmail session | Envelope forwarded or opened via a temporary sales portal |
Under California Uniform Electronic Transactions Act (UETA, Cal. Civ. Code § 1633.9), an electronic record or signature is attributable to a person only if it was the act of that person. The act of the person may be shown in any manner, including showing the efficacy of any security procedure applied to determine the person to which the electronic record or signature was attributable. When the IP address belongs to the installer's device, Mosaic cannot meet its burden of proving mutual assent.
The California CLRA Hammer: 30-Day Pre-Suit Notice
The Consumer Legal Remedies Act (Cal. Civ. Code § 1750 et seq.) was enacted to protect consumers against unfair and deceptive business practices. Under Cal. Civ. Code § 1770, prohibited practices include:
- Representing that a transaction confers rights, remedies, or obligations that it does not have (§ 1770(a)(14)).
- Inserting an unconscionable provision in the contract (§ 1770(a)(19)).
- Disbursing commercial loan obligations based on fraudulent representations of completion.
The Mandatory 30-Day Notice (Cal. Civ. Code § 1782)
Before a homeowner can file a civil complaint for damages under the CLRA, they must satisfy a strict procedural condition:
- Provide written notice to the seller and lender by certified or registered mail, return receipt requested.
- State the particular alleged violations of Section 1770.
- Demand that the company correct, repair, replace, or otherwise rectify the deceptive conduct within 30 days of receiving notice.
What Happens If Mosaic Fails to Cure
If Mosaic refuses or fails to rectify the situation within the 30-day statutory window (by canceling the loan, refunding unauthorized debits, and correcting credit reports), the consumer is permitted to amend or file their lawsuit seeking:
- Actual Damages: Financial losses incurred, roof repair expenses, and interest paid.
- Restitution: Complete disgorgement of all funds paid under the fraudulent contract.
- Punitive Damages: Financial penalties assessed against the defendant for willful or reckless deceptive conduct.
- Statutory Attorney's Fees: Under Cal. Civ. Code § 1780(e), reasonable attorney's fees are awarded to a prevailing plaintiff. This fee-shifting provision is why specialized consumer attorneys routinely take legitimate CLRA forgery cases on contingency with zero out-of-pocket costs to the consumer.
Stopping Collections Under the Rosenthal Act & FCRA
When an unauthorized loan enters default, lenders frequently outsource collection to third-party agencies. This creates severe pressure on homeowners who fear losing their homes or having their credit ratings destroyed.
The Rosenthal Fair Debt Collection Practices Act
California's Rosenthal Act (Cal. Civ. Code § 1788 et seq.) incorporates the federal FDCPA but extends liability directly to original creditors, not just third-party collectors. Under California law:
- Creditors cannot make false statements regarding the character, amount, or legal status of any debt.
- Creditors cannot communicate with a consumer once notified that the consumer is represented by legal counsel.
- Under Cal. Civ. Code § 1788.18, if a debtor notifies a creditor in writing that they are the victim of identity theft or forgery, provides a police report and an identity theft affidavit, the debt collector must cease all collection activities until an investigation verifies the legitimacy of the debt.
Credit Reporting Freezes (FCRA, 15 U.S.C. § 1681s-2(b))
Lenders cannot willfully report disputed debts as delinquent without reporting the debt as disputed. Once a formal dispute is submitted with an accompanying police report:
- The furnisher (Mosaic) must conduct a mandatory investigation within 30 days.
- If the signature cannot be authenticated, the tradeline must be deleted from Equifax, Experian, and TransUnion.
Step-by-Step 30-Day Action Protocol
If you discover forged initials or unauthorized payouts on a Mosaic solar loan in California, execute the following steps immediately.
Step 1: Demand Audit Trail ──> Step 2: Police Report ──> Step 3: CLRA 30-Day Notice ──> Step 4: DFPI/CSLB Complaints
Step 1: Demand the Full Contract File and Audit Certificate
Send a written request to Mosaic demanding:
- The full executed Loan Agreement, including all change orders and addenda.
- The DocuSign Certificate of Completion showing IP addresses, geolocations, and timestamp data.
- The Proof of Installation / Milestone Disbursement Authorizations signed by the contractor and consumer.
Step 2: File an Identity Theft Report & Police Report
Visit IdentityTheft.gov (managed by the FTC) and generate an official Identity Theft Affidavit regarding the unauthorized loan. File a police report with your local municipal police department or sheriff's office detailing the forgery of your electronic initials.
Step 3: Serve the Formal CLRA 30-Day Demand Letter
Draft and serve a formal demand letter via USPS Certified Mail with Return Receipt Requested addressed to:
- Solar Mosaic LLC, Legal & Compliance Department
- Any assigned collection agency or loan servicer
The letter must explicitly cite:
- California Civil Code § 1782 (CLRA pre-suit notice).
- California Civil Code § 1788.18 (Rosenthal Act identity theft notification).
- FTC Holder Rule (16 CFR § 433).
- Detailed factual discrepancies in the DocuSign audit trail.
- Demand for complete loan cancellation, release of UCC-1 fixture filing, refund of prior payments, and removal of derogatory credit entries within 30 days.
Step 4: Submit Regulatory Complaints
Simultaneously file formal complaints with:
- California Department of Financial Protection and Innovation (DFPI): Regulates non-bank financial lenders in California.
- California Contractors State License Board (CSLB): Submits complaints against the contractor's license bond for abandonment and fraud.
- Consumer Financial Protection Bureau (CFPB): Submits complaints against the lender for unauthorized credit origination.
FAQ
Can Mosaic hold me liable for a loan if I didn't initial the documents?
No. Under basic contract law and the California Uniform Electronic Transactions Act (Cal. Civ. Code § 1633.9), a valid contract requires mutual assent. An electronic signature or initial is only binding if it was the act of the consumer. If an installer, sales agent, or third party placed your initials on the contract or milestone release without your authorization, the contract is voidable due to forgery and lack of assent.
What happens if Mosaic disbursed funds to the contractor before the solar was turned on?
Lenders typically require milestone verification before releasing funds. If Mosaic released money to an installer based on a forged completion certificate or without verifying municipal permit sign-off and utility permission to operate (PTO), Mosaic disbursed funds at its own peril. Under the FTC Holder Rule (16 CFR § 433), borrowers can assert the contractor's failure of performance against Mosaic to prevent collection and demand debt cancellation.
How does a 30-day California CLRA letter work against a solar lender?
Under California Civil Code § 1782, a consumer must give the company 30 days' written notice by certified mail identifying the specific deceptive practices under Section 1770 and demanding correction. If the lender corrects the violation (canceling the loan and repairing credit) within 30 days, damages cannot be awarded. If the lender fails or refuses to cure within 30 days, the homeowner can sue for actual damages, punitive damages, and mandatory attorney's fees.
Can a collection agency ruin my credit while a solar loan is disputed for forgery?
Not legally. Under the California Rosenthal Fair Debt Collection Practices Act (Cal. Civ. Code § 1788.18) and the Fair Credit Reporting Act (FCRA), once you submit a written notice of dispute accompanied by an official police report or FTC Identity Theft Affidavit, debt collectors and furnishers must cease collection efforts and verify the debt. Continuing to report derogatory data without investigating exposes the furnisher to statutory penalties.
What evidence do I need to prove my initials were forged on a digital contract?
You need the electronic signature platform's Certificate of Completion (such as DocuSign or Adobe Sign). This document details the signer's IP address, device operating system, network host, and timestamps. Showing that the IP address belongs to the solar company's office or representative's cellular hotspot rather than your home network provides objective technical proof of forgery.
What should I do if the solar contractor went out of business after getting paid?
If the contractor is insolvent or filed for bankruptcy, your legal remedy shifts entirely to the lender who holds the financing contract. Under the FTC Holder Rule, the lender is legally subject to all claims and defenses you could assert against the seller. You do not lose your defenses simply because the contractor is bankrupt.
Do I need to pay an attorney out-of-pocket to handle a CLRA claim?
Generally, no. The California Consumer Legal Remedies Act (Cal. Civ. Code § 1780(e)) and the federal fee-shifting statutes (FDCPA, FCRA) mandate that the defendant pay the consumer's reasonable attorney's fees if the consumer prevails. Consumer protection attorneys routinely evaluate documented forgery and unauthorized disbursement cases on a contingency or statutory fee-recovery basis.
Next Research Steps
Use these resources to connect this issue with the broader solar scam pattern, the relevant legal framework, and the next practical action.
Solar panel scams
Start with the main solar panel scams guide for the broad definition and recovery roadmap.
Solar financing fraud compensation
Use this guide for loan, dealer-fee, payment-jump, PACE, lease, and lender-defense issues.
Homeowner legal rights
Review cancellation, rescission, UDAP, TILA, Holder Rule, arbitration, and lawsuit options.
Solar fraud by state
Compare state and city issues against the national solar fraud map.
Trapped in a predatory loan?
FTC Holder Rule & cancellation rights